

 Facebook
 X
 Pinterest
 Copy Link
Planning To Sell in 2027? Start Prepping Now.
If selling your house is on your calendar for 2027, you may be thinking you’ve got plenty of time. Maybe you’re aiming for January. Maybe you’re waiting for spring. Either way, next year probably feels far enough away that getting ready can wait, too.
But waiting until 2027 to sell doesn’t mean waiting until 2027 to get started.
Today’s buyers have more homes to choose from than they’ve had in years. So, if you want your house to stand out when it’s time to list, a little preparation now can make a big difference later.
How Early Should You Start Getting Ready?
As a general rule of thumb, Zillow recommends giving yourself about 2-3 months to get your house ready to list. And that makes sense when you consider that the vast majority of sellers (78%) did at least one home improvement project before their house hit the market.
That gives you plenty of time to decide what to fix, find contractors, get on their schedules, actually make the updates, and get everything ready for photos and showings.
But don’t worry – that doesn’t mean every seller had some big to-do. The most common? Interior painting (see graph below):
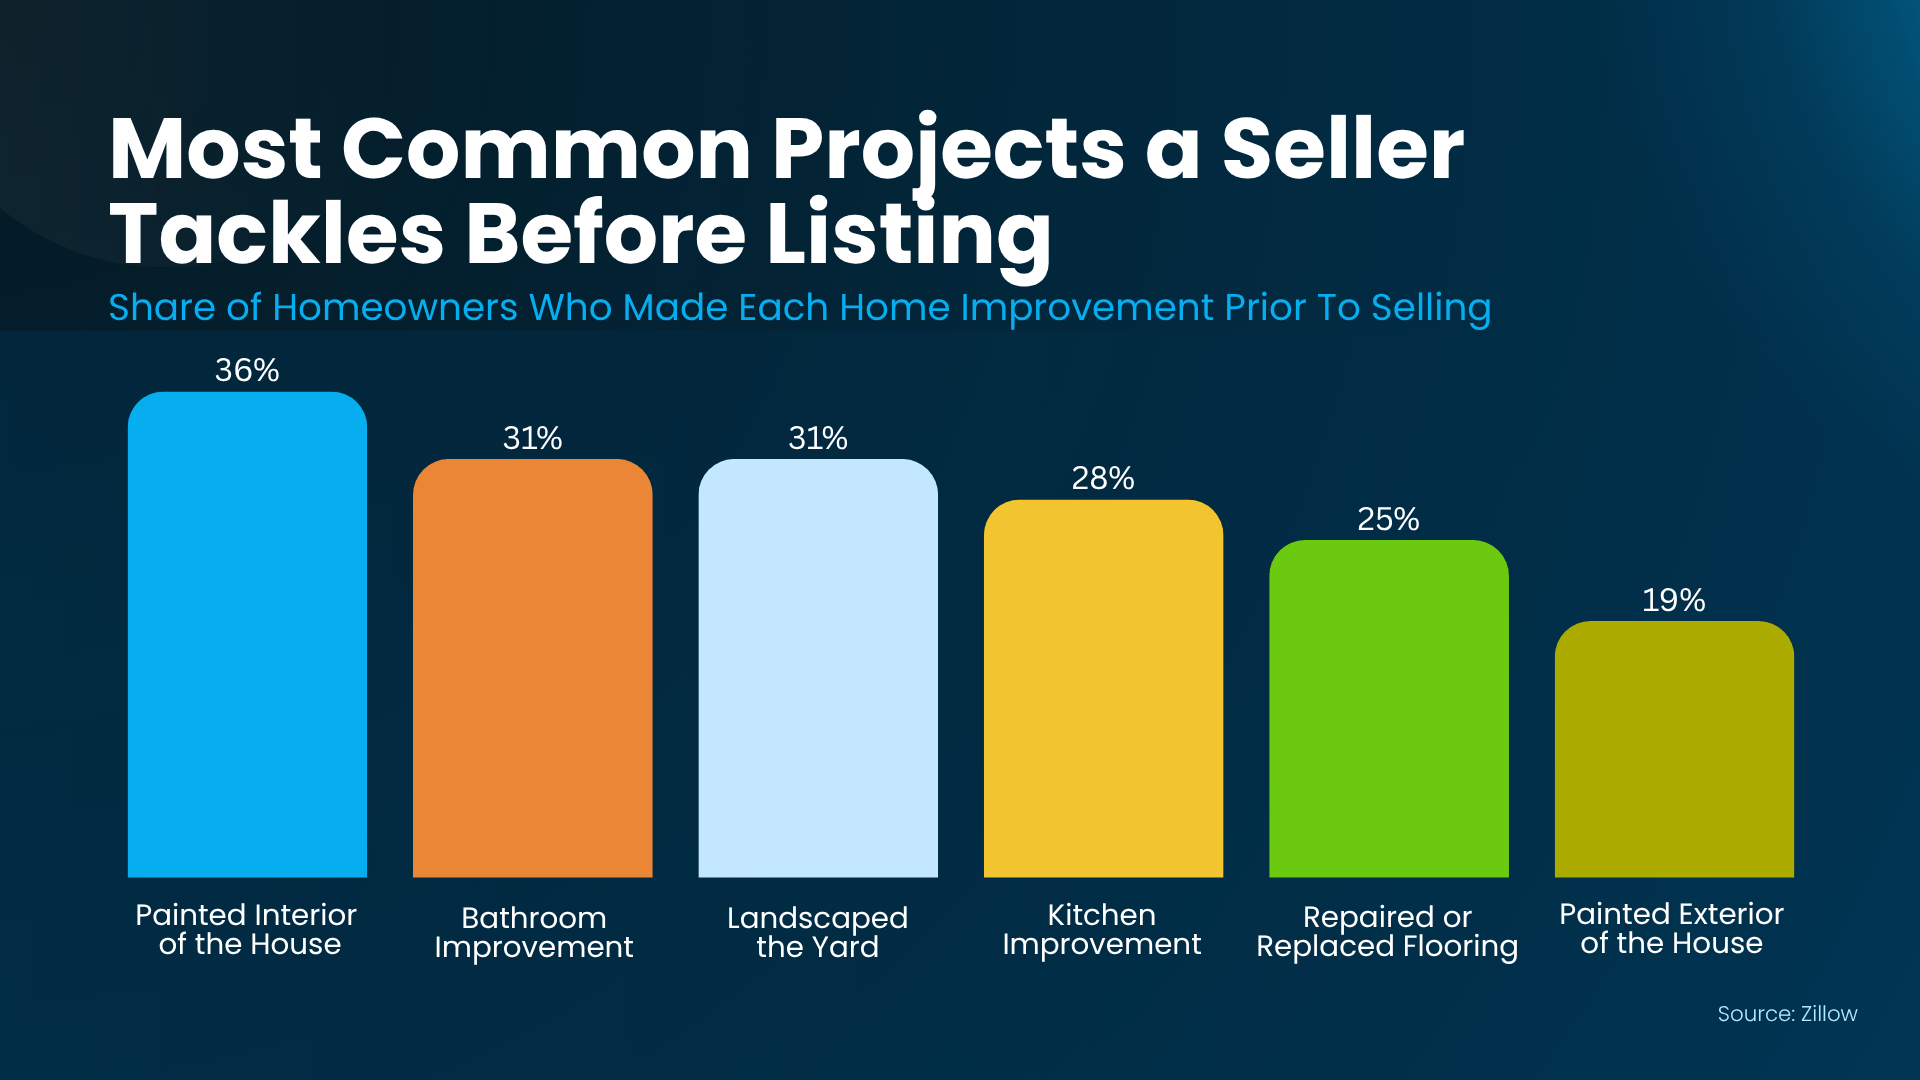
That certainly doesn’t mean you need to tackle everything on this list. You may not need to do any of it. But odds are there’s at least one project you’ll want to do. And starting that conversation now gives you a leg up before next year.
Here’s how to tackle it.
1. Talk to an Agent Before Starting Any Projects
While you might have a long list of things you think need updating, that doesn’t mean they’re all worth the time, effort, or money.
An agent will help you figure out which projects deserve a spot on your to-do list based on what buyers want most and what other sellers are doing. That way, you’re not investing in updates that won’t make much of a difference when you sell.
2. Get Ahead with a Pre-Listing Inspection
One thing your agent may recommend today is that you go ahead and get a pre-listing inspection. It’s basically your cheatsheet to what a buyer’s inspection may turn up later on.
And now that buyers have more options, they’re pickier – and you don’t want anything popping up in an inspection that could put them off.
For example, you know that HVAC system you’ve been hoping will make it through one more season? Now’s a good time to give it some attention – along with anything else you know needs a little TLC. That way a repair you could’ve handled months ago won’t become a surprise in the middle of your sale.
According to Angi, a pre-listing inspection typically costs $300-600 and that can be money well spent. As the National Association of Realtors (NAR) explains:
“An inspector will be able to give you a good indication of the trouble areas that will stand out to potential buyers, and you’ll be able to make repairs before open houses begin.”
The advantage isn’t just knowing what may come up, but being able to get ahead of it and space out the projects on your own schedule. So you don’t feel stressed during go-time.
3. Save the Final Touches for Closer to Listing Day
But remember, not everything needs to happen right away. Some things are better saved for when you’re closer to listing.
Think deep cleaning, staging, touching up paint, and tidying up the landscaping. Those are the finishing touches that’ll help your house look its best when buyers walk through the door.
But there’s one thing you can start anytime: decluttering. Go ahead and tackle the closets, garage, or storage room you’ve been avoiding. Future you will appreciate having a few less boxes to pack.
The idea isn’t to get everything done today. It’s to spread the work out so you’re not scrambling when listing day arrives. As Redfin puts it:
“Smart preparation leads to a smoother sale, stronger offers, and fewer surprises during closing. . . Homes that are clean, well-staged, priced right, and professionally photographed tend to sell quickly.”
Bottom Line
You don’t need to spend the rest of the year renovating your house or packing up your life. But you can start making a plan.
The earlier you figure out what needs to be done, the more time you’ll have to do it right. And that means less rushing, fewer last-minute surprises, and a better chance to make a great first impression when you’re ready to sell.
Thinking about selling in 2027? Let’s talk about what your house needs, what it doesn’t, and how to get everything ready on your timeline.
The Housing Market Is on Solid Ground, Even with More Foreclosures
It’s been nearly two decades since the 2008 housing crash, but the word “foreclosure” can still make people uneasy. And if you’re planning a move, you may be wondering if more foreclosures will flood the market with homes for sale – especially if you’ve seen the headlines lately.
Buyers may be hoping for a rush of bargains. Sellers may be bracing for more competition. The latest data points to neither, and knowing why can help you plan your next move with confidence.
A Modest Rise from a Low Starting Point
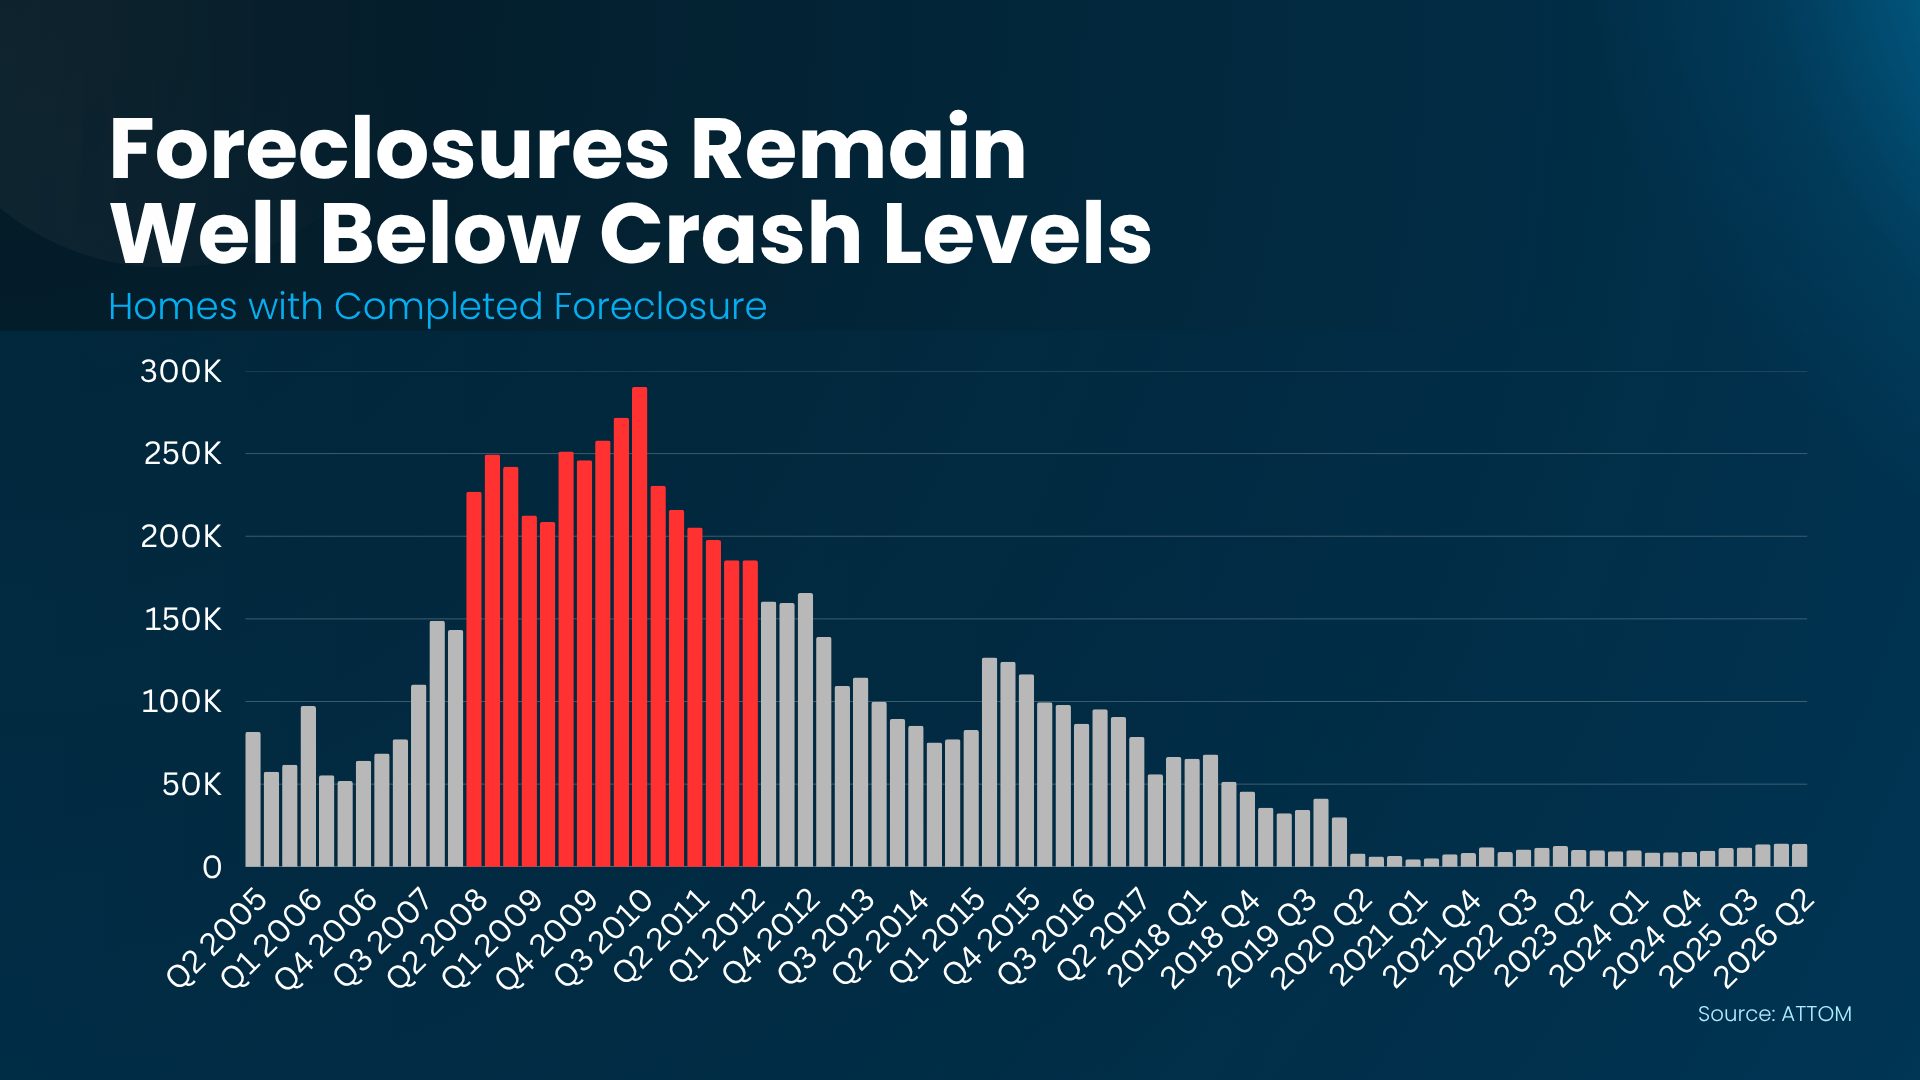
Completed foreclosures are up 33% from last year, according to ATTOM. That sounds like a big leap, but context helps.
Even with that increase, foreclosures are still about 26% below where they were in the first half of 2020.
Zoom out further, and today’s activity is a small fraction of what the market saw during the 2008 crash. Lenders completed about 28,000 foreclosures in the first half of 2026, according to ATTOM. Compare that to the crash years in red, when lenders often completed more than 200,000 in the span of a few months (see graph below):
Experts say today’s numbers reflect a housing market that’s still in good shape. As Rob Barber, CEO at ATTOM, explains:
“While some homeowners are still facing financial challenges, overall foreclosure volumes remain well below historical norms and the broader housing market continues to demonstrate resilience.”
And here’s why we can absorb the slight uptick in foreclosures we are seeing.
Homes for Sale Are Back in a Balanced Range
During the crash, a lot of homeowners either lost their homes to foreclosure or were forced to sell, which left the market overwhelmed with houses for sale. That isn’t happening now.
One way to see this is through months’ supply, which measures how long it would take to sell every home on the market at the current pace. Four to six months is considered balanced.
Right now, it’s about 4.8 months, according to the National Association of Realtors (NAR). That’s pretty well-balanced, and less than half of where it peaked around the last crash (see graph below):
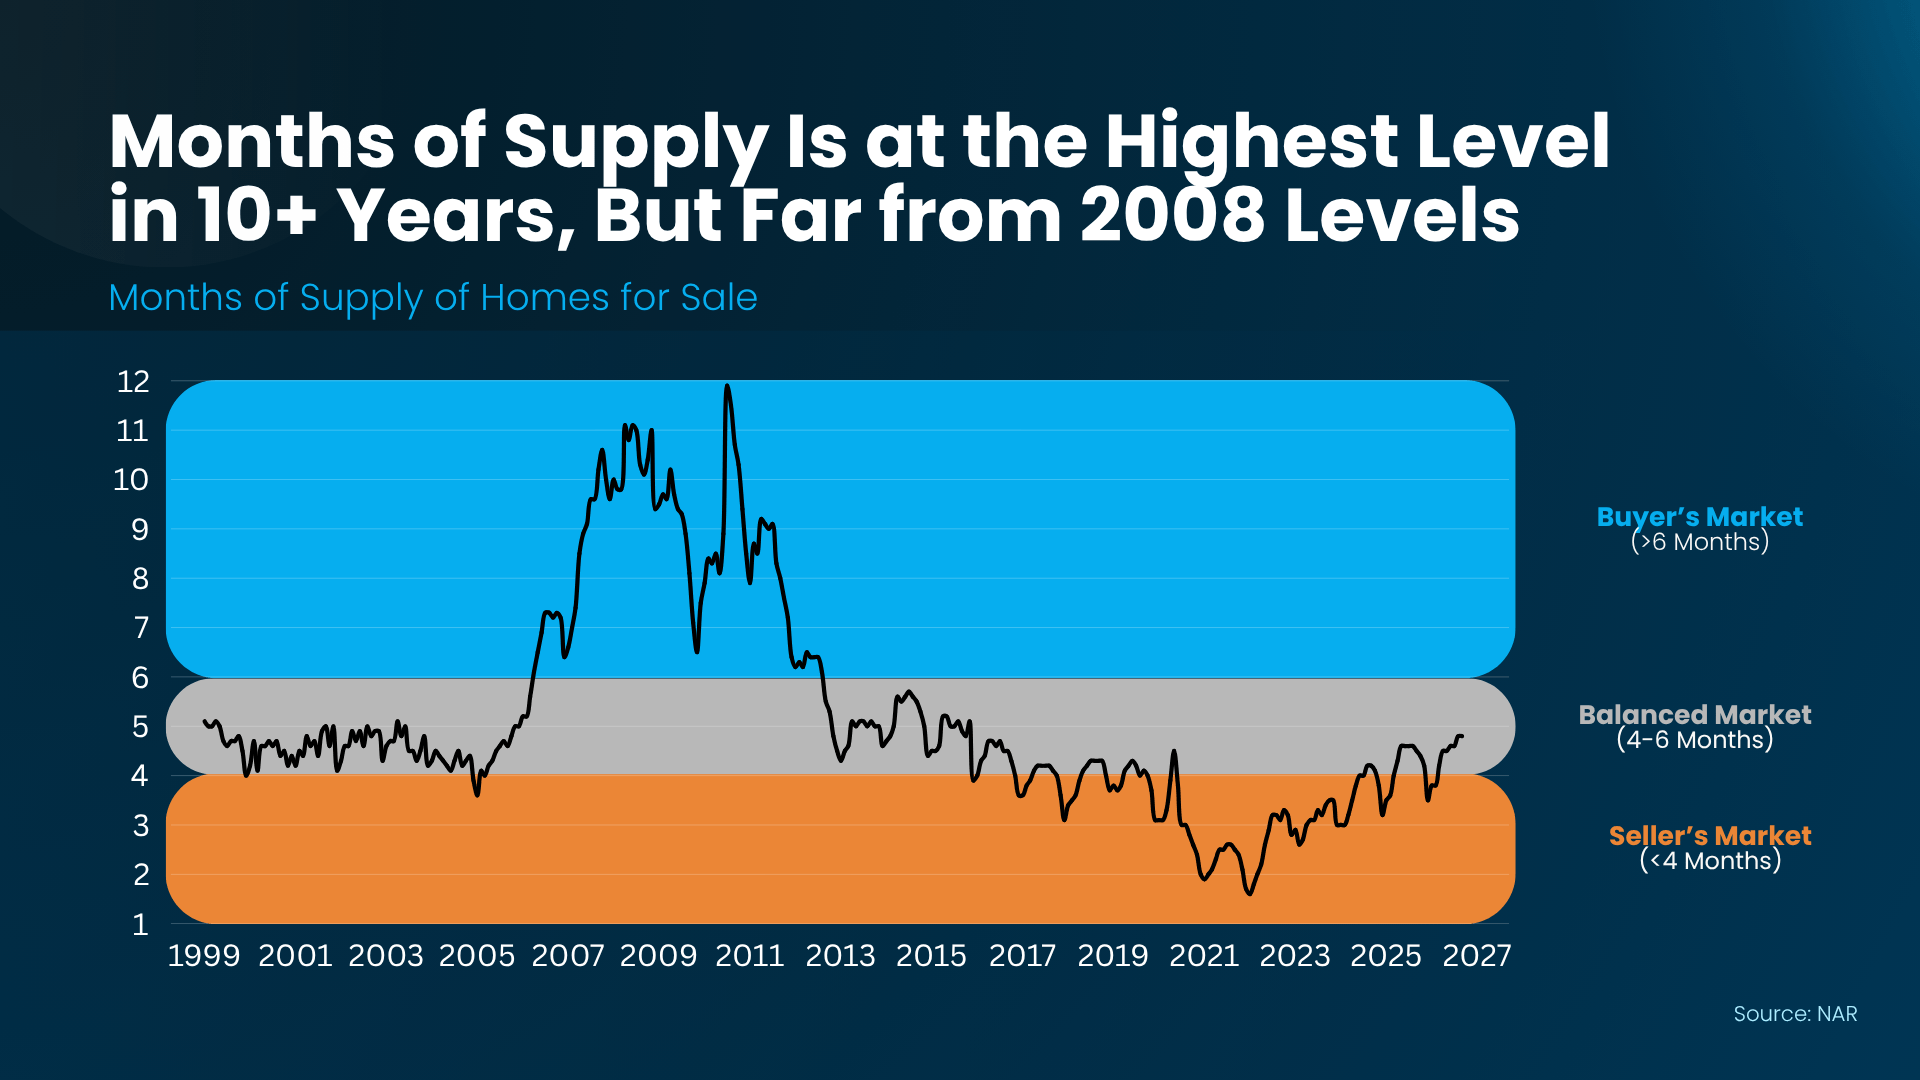
If foreclosures were really surging, you’d see it in the number of homes for sale. As Logan Mohtashami, Lead Analyst at HousingWire, explains:
“. . . a surge of actual foreclosures in 2026 would have easily put the inventory data much higher in 2026.”
Equity Gives Today’s Homeowners Options
Equity is a big reason there’s no surge of distressed sales. Data from the Census Bureau and ATTOM shows nearly two in three homeowners have paid off their mortgage or have more than 50% equity. And Cotality says the average homeowner has about $310,000 in equity.
If a homeowner with equity hits a rough patch, they can usually sell their house, pay off the loan, and walk away with money in their pocket instead of facing foreclosure. That’s an option many people didn’t have during the crash. According to HousingWire, nearly one in four homes were underwater back in 2010.
Being underwater means owing more on your mortgage than your home is worth, which makes selling a lot harder. Today, just 2% of homeowners are considered seriously underwater (see graph below):
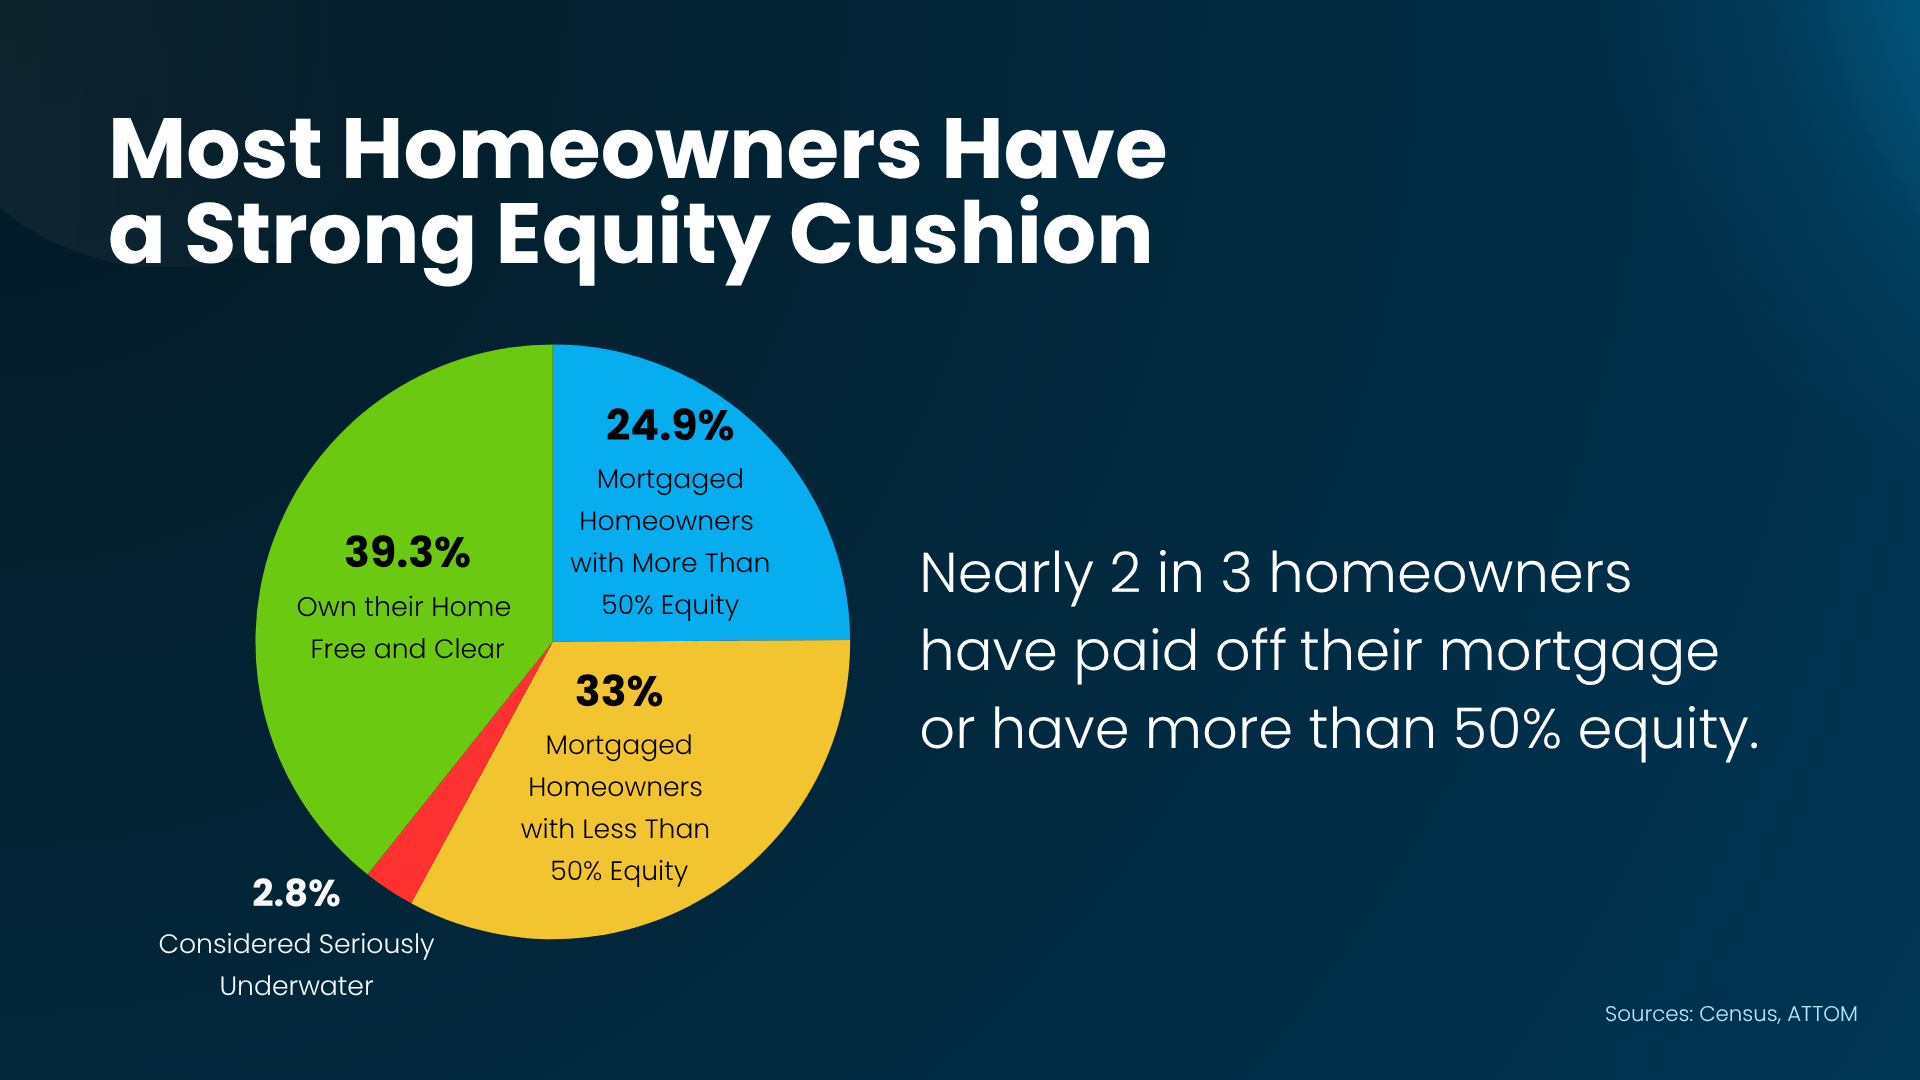
Not every homeowner has that kind of equity, but most do, and that’s what puts a ceiling on how high foreclosures can go.
Bottom Line
If rising foreclosures have you questioning where the housing market is headed, the data says it’s in good shape. The supply of homes for sale is balanced, and most homeowners have plenty of equity.
Have questions about what you’re seeing online, our local market, or about how much equity you have? Let’s talk.
Today’s Market Could Be a Win for Veterans Looking To Buy a Home
If you’re a veteran or active-duty service member who’s been hoping to buy a home, you may have more going for you in today’s housing market than you realize.
VA home loans already come with some pretty powerful benefits. But now, with more homes for sale and buyers having more room to negotiate in many markets, those benefits could go even further.
And if you’ve ever heard that buying with a VA loan is harder, takes longer, or puts you at a disadvantage, there’s something else you should know… a lot of what people believe about VA loans simply isn’t true.
The Benefits of VA Home Loans
Today, nearly 4 million service members and veterans have an active VA home loan. And according to the Department of Veterans Affairs (VA), more than 343,000 homes were purchased using VA loan benefits in its most recent reported fiscal year. And it’s easy to see why.
For eligible veterans and service members, VA loans offer advantages that can make buying a home more affordable, including:
- No down payment required for many eligible borrowers.
- No monthly mortgage insurance, even with no down payment.
- Competitive mortgage rates that can help lower monthly payments.
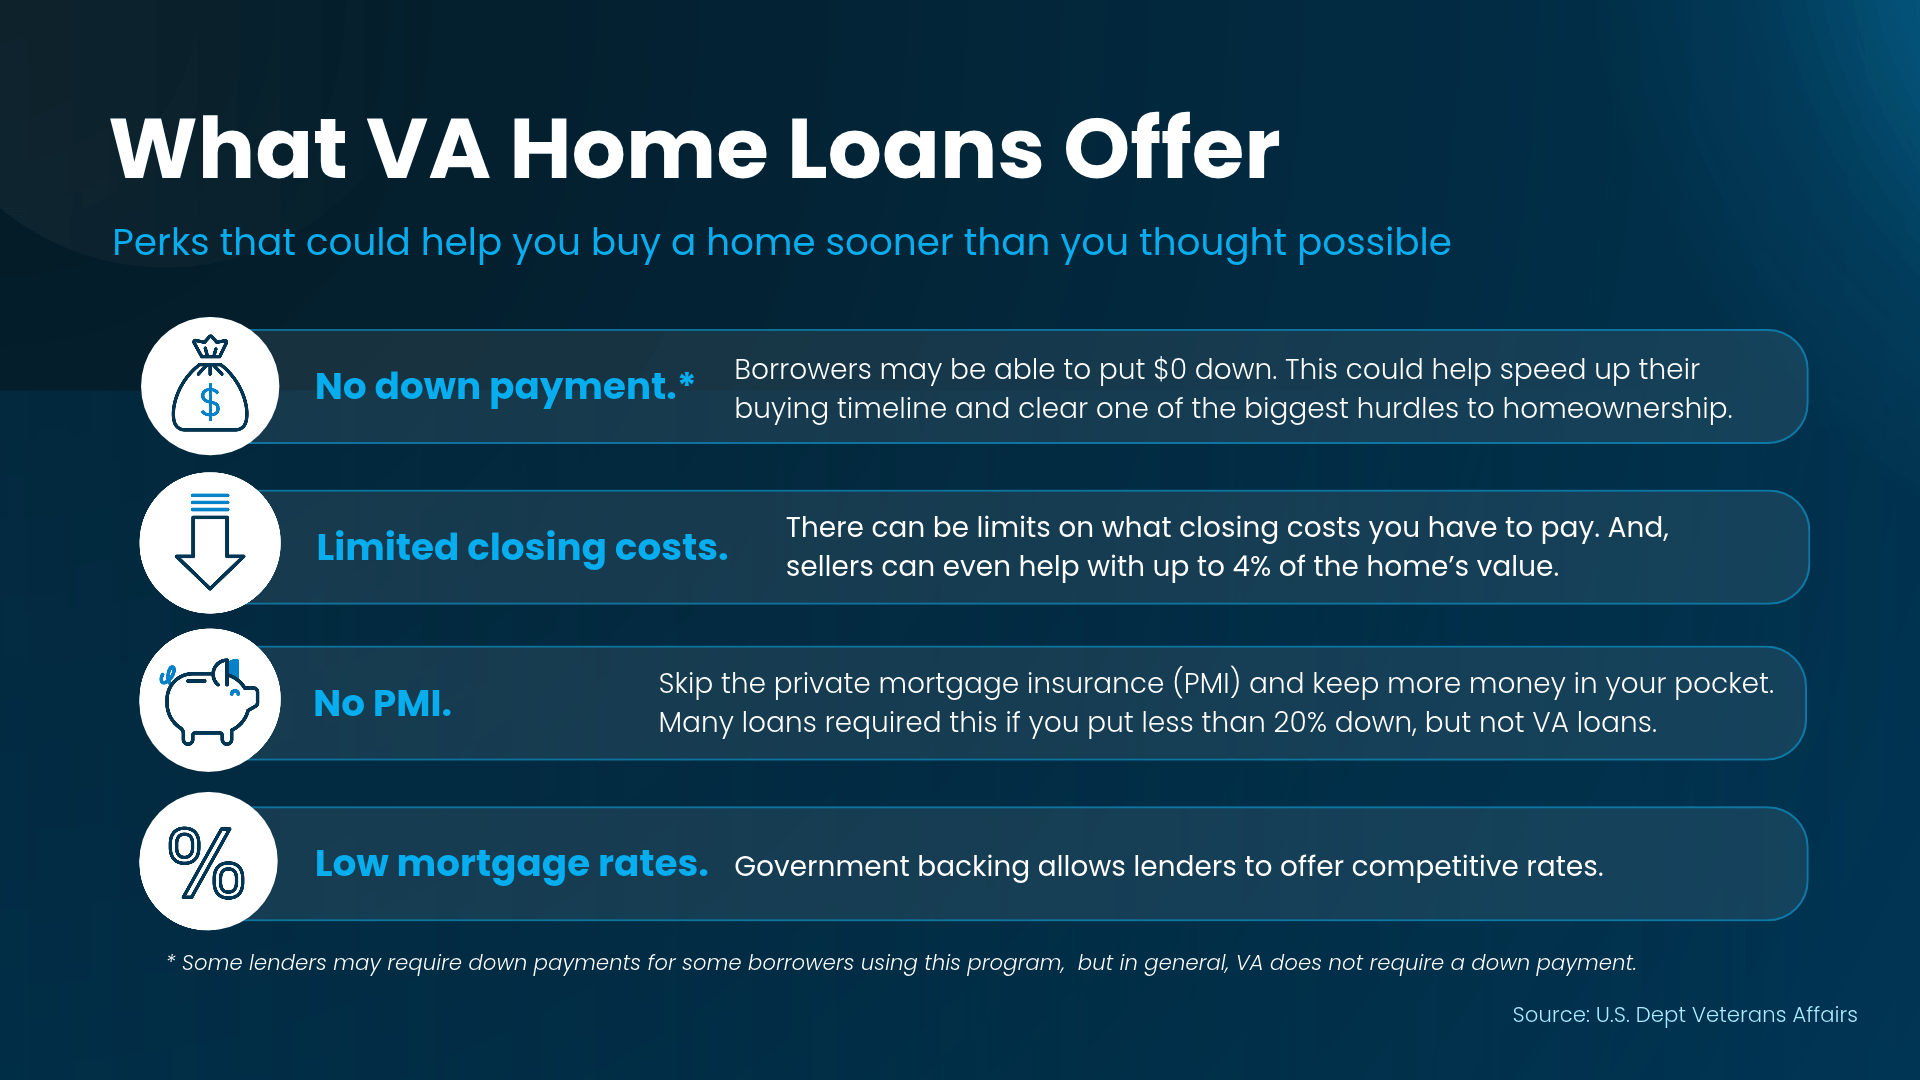
Benefits like this are powerful in any market – and even more so today. That may be why VA loan usage has grown for the last two years in a row.
Why Today’s Market Could Be Different for VA Buyers
A few years ago, when homes were getting multiple offers and buyers were competing for nearly every listing, VA buyers sometimes had a harder time getting their offers accepted.
A 2021 survey from the National Association of Realtors (NAR), found 89% of sellers were likely to accept an offer from a buyer using a conventional loan. But only 30% were likely to accept one using an FHA or VA loan.
The reason? Some sellers were concerned that VA financing would take longer, be more difficult to close, and require them to pay more in costs and repairs. But those concerns don’t necessarily reflect how VA loans actually perform.
VA Home Loan Myths vs. Reality
A white paper from Vetted VA based on 2025 mortgage data busted a lot of VA loan myths:
Myth #1: VA loans get denied more often than other loans.
- The Reality: VA loans actually have the lowest denial rate. Just 8.2% of VA purchase applications were denied, compared to 15.0% for conventional loans, 12.8% for FHA loans, and 12.5% for USDA loans.
Myth #2: VA financing is less reliable.
- The Reality: 90% of VA home loan applications that reached underwriting made it to closing, compared to 81% for conventional loans.
Myth #3: VA appraisals take longer.
- The Reality: VA loan appraisals typically take 7–10 business days, similar to conventional and FHA loans.
Myth #4: Sellers have to pay all the closing costs for VA buyers.
- The Reality: VA buyers can pay many standard closing costs themselves. Buyers and sellers can also negotiate which eligible costs the seller will cover.
Today’s Market Gives VA Buyers More Leverage
Since there are more homes for sale and fewer buyers competing in many areas, sellers may be more open to different financing options than they were a few years ago. And the opportunity doesn’t stop at getting your offer accepted.
Depending on the house and your local market, you may also be able to negotiate a lower price, ask for repairs, or request help with closing costs.
VA guidelines allow sellers to cover the buyer’s normal closing costs, plus concessions of up to 4% of the home’s value.
Think about what that combination could mean. You may be able to buy with no down payment, avoid mortgage insurance, and negotiate help with some of the other expenses that come with buying a home.
That could mean keeping thousands of dollars in your savings instead of spending them upfront, giving you more breathing room after you get the keys.
Bottom Line
If you’re active duty, you’ve served, or you know someone who has, connect with a local agent and a trusted VA-approved lender to see what you qualify for.
Your VA home loan benefit and today’s market could be a powerful combination.
Selling Your Home? What You Should Know About Price Cuts vs. Rate Buydowns.
In today’s market, a growing number of sellers are opting to do something called a price cut – especially when their house has been on the market for a while without any bites.
According to HousingWire Data as many as 4 in 10 (43%) sellers are going this route – that’s the highest it’s been in 4 years. But what if there’s another (potentially better option) for your bottom line? And it’s just as appealing, if not more so, to today’s buyers?
Enter the rate buydown.
Why Buyers Expect a Deal
First, let’s set the stage on why some compromise may be necessary in today’s market.
In September, Redfin says there were 63% more sellers than buyers in the market. And with so many sellers active and relatively few buyers by comparison, those purchasers are realizing they have more power. And as mortgage rates continue to put a squeeze on their budgets, they’re leaning in and using it.
One of the most common negotiation points? The price.
That’s because they want to feel like they’re getting a deal and they want to see their monthly payment drop. And since buyers can’t control rates, the price feels like the most obvious lever to pull.
But the savviest sellers realize being flexible doesn’t always mean a lower price, paying for a buyer’s rate buydown might work better.
What Is a Rate Buydown?
A buydown is money paid at closing to lower the buyer’s mortgage rate. When you pay it as the seller, you are paying some of the buyer’s interest ahead of time, so the buyer gets a lower rate and monthly payment. And that’s especially appealing to today’s buyers.
- Temporary buydowns lower the rate for the first few years, then it goes back to the full rate. The more years a buydown covers, the more it costs. These work well for buyers who expect to refinance within a certain amount of time.
- A permanent buydown lowers the rate for the whole loan. These are paid for with “discount points.” One point costs 1% of the loan. According to FICO, each point generally lowers the rate by about a quarter of a percent. This type of buydown works well for buyers who plan to stay in the home for a long time.
Same Money, Different Results
And here’s why these can be a win-win for both buyers and sellers. Rate buydowns help sellers stand out in a crowded market and they can have a bigger impact on your buyer than a price cut would.
Here’s an example to show you what that could look like.
Let’s say you’re willing to make a $10,000 concession to help get the deal done. Take a look at these three ways to spend that money and the impact they could have on a buyer’s $420,000, 30-year fixed loan at 7%:
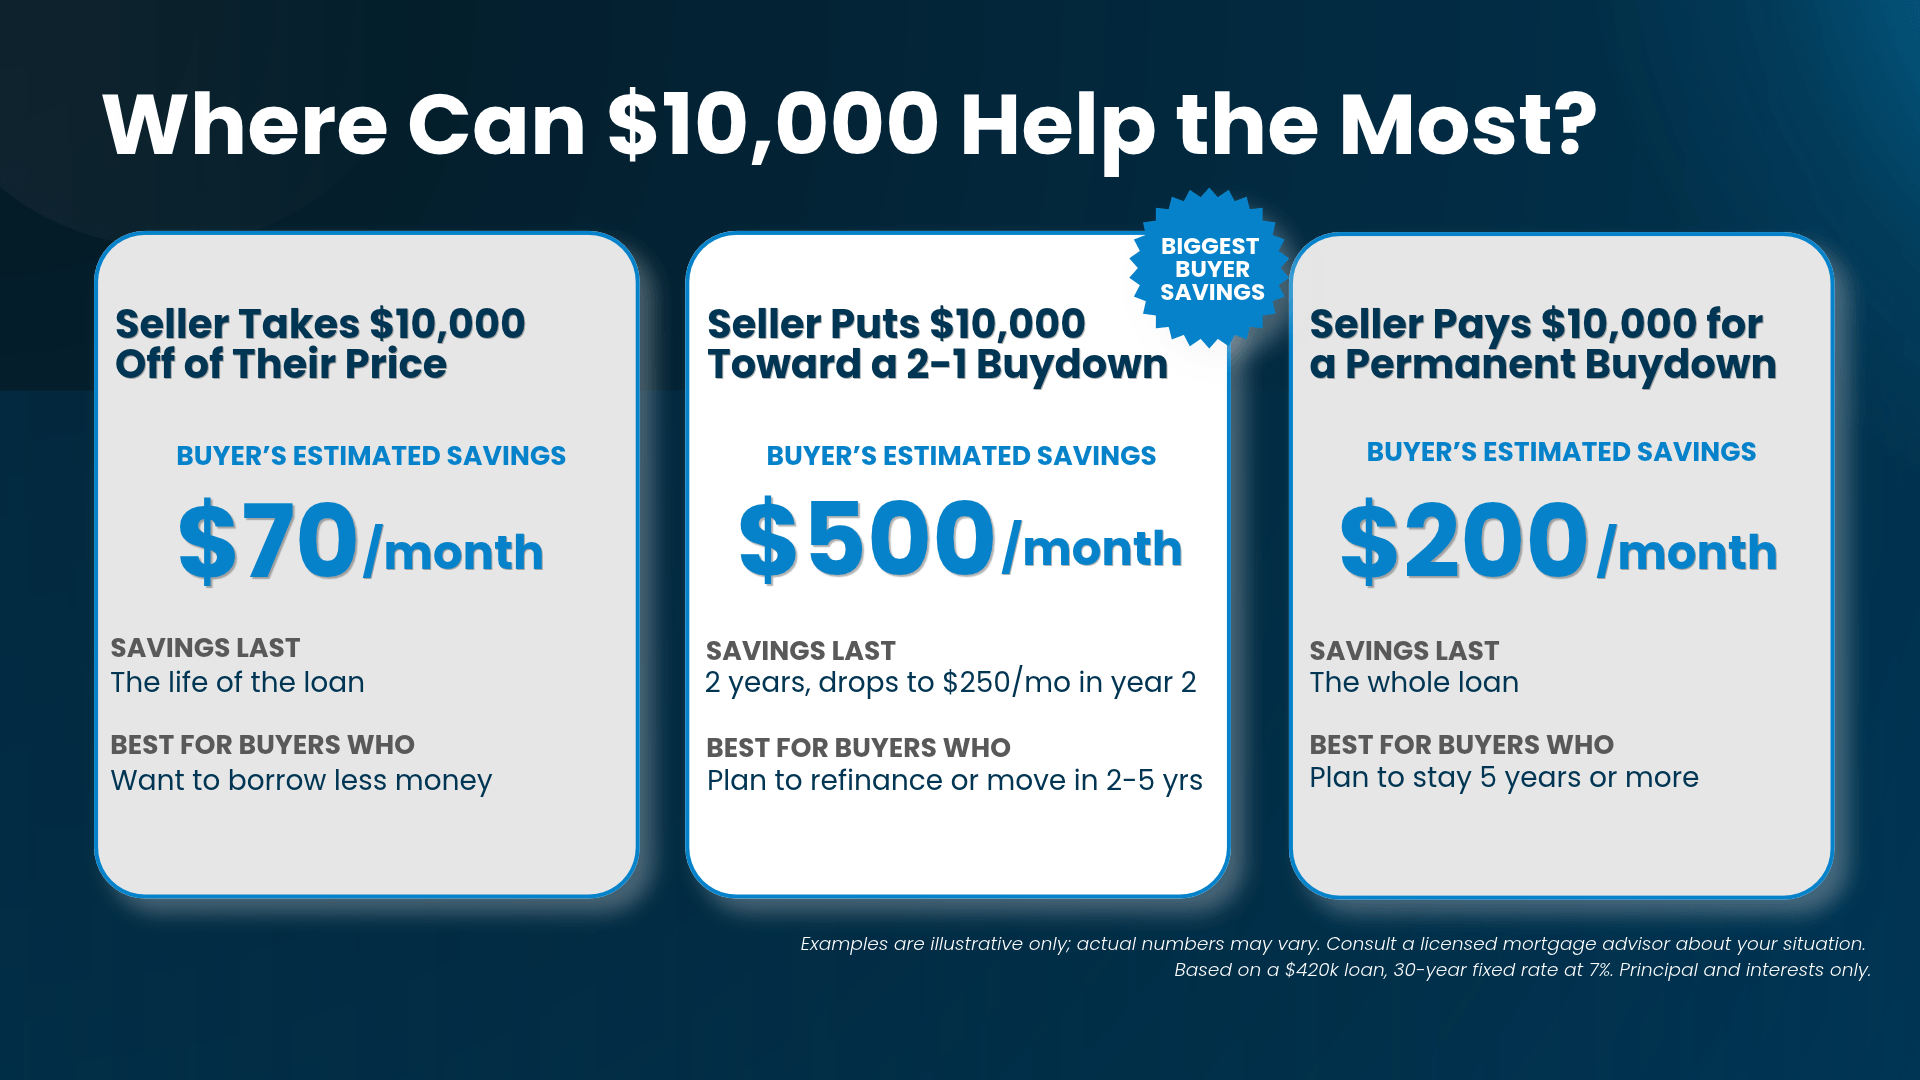
It’s the same $10,000 from the seller. But a 2-1 buydown saves the buyer about eight times more each month in the first year.
And since most buyers shop by monthly payment, that’s what grabs their attention.
That’s what makes a rate buydown worth considering. Instead of reducing your asking price, you may be able to use that same money to have a bigger impact on your buyer’s monthly payments. And depending on what matters most to that buyer, the immediate savings could be more appealing than a price reduction.
The key is working with your agent and the buyer’s lender to compare the options and see which one makes the most sense.
Things To Know
- Loan programs cap how much a seller can pay toward a buyer’s costs.
- Money toward buydowns doesn’t limit what else a buyer may ask a seller to pay for. Buyers may still ask for repairs or other concessions.
- Putting the buydown offer in your listing lets agents and buyers know it’s an option.
- Your agent can run scenarios on buydowns and other costs of selling in advance so you’re prepared when an offer comes in.
As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:
“Home sellers need to be realistic about local market conditions, which could require price discounts and other incentives to attract buyers.”
And sellers who offer solutions like buydowns can make meaningful impact where home buyers need it most: in their wallets.
Bottom Line
When you’re looking for ways to make your house more appealing to buyers, a price reduction isn’t your only option. A mortgage rate buydown could help a buyer save more each month, especially in the early years of their loan.
Talk to your agent or a trusted lender which incentives could make the biggest difference for buyers in our market, while still protecting your bottom line.
Why Builders May Be More Motivated To Sell Than Homeowners
Here’s something most homebuyers don’t think about. When the housing market slows down, homeowners and builders don’t always respond the same way.
Think about it. If you’re selling your house and aren’t getting the offers you want, you could make the choice to take it off the market and stay put, and wait for things to improve.
But builders? They may be more motivated to stay the course.
They’ve already invested money in building those houses. And every completed home that sits unsold means money tied up in a property, plus ongoing costs that can add up.
That’s why some builders may be more motivated to negotiate right now. And that could work in your favor.
Fewer Buyers Are Making Moves. And Builders Are Feeling It.
You’ve probably seen the headlines. According to the latest report from the National Association of Realtors (NAR), pending home sales – homes that have gone under contract but haven’t closed yet – fell 7.3% in September and 11.3% compared to last year.
Why? Higher mortgage rates are making it harder for buyers to make the numbers work. Now, that report tracks existing homes, not new construction. But we’re seeing signs of the same slowdown on the builder side, too.
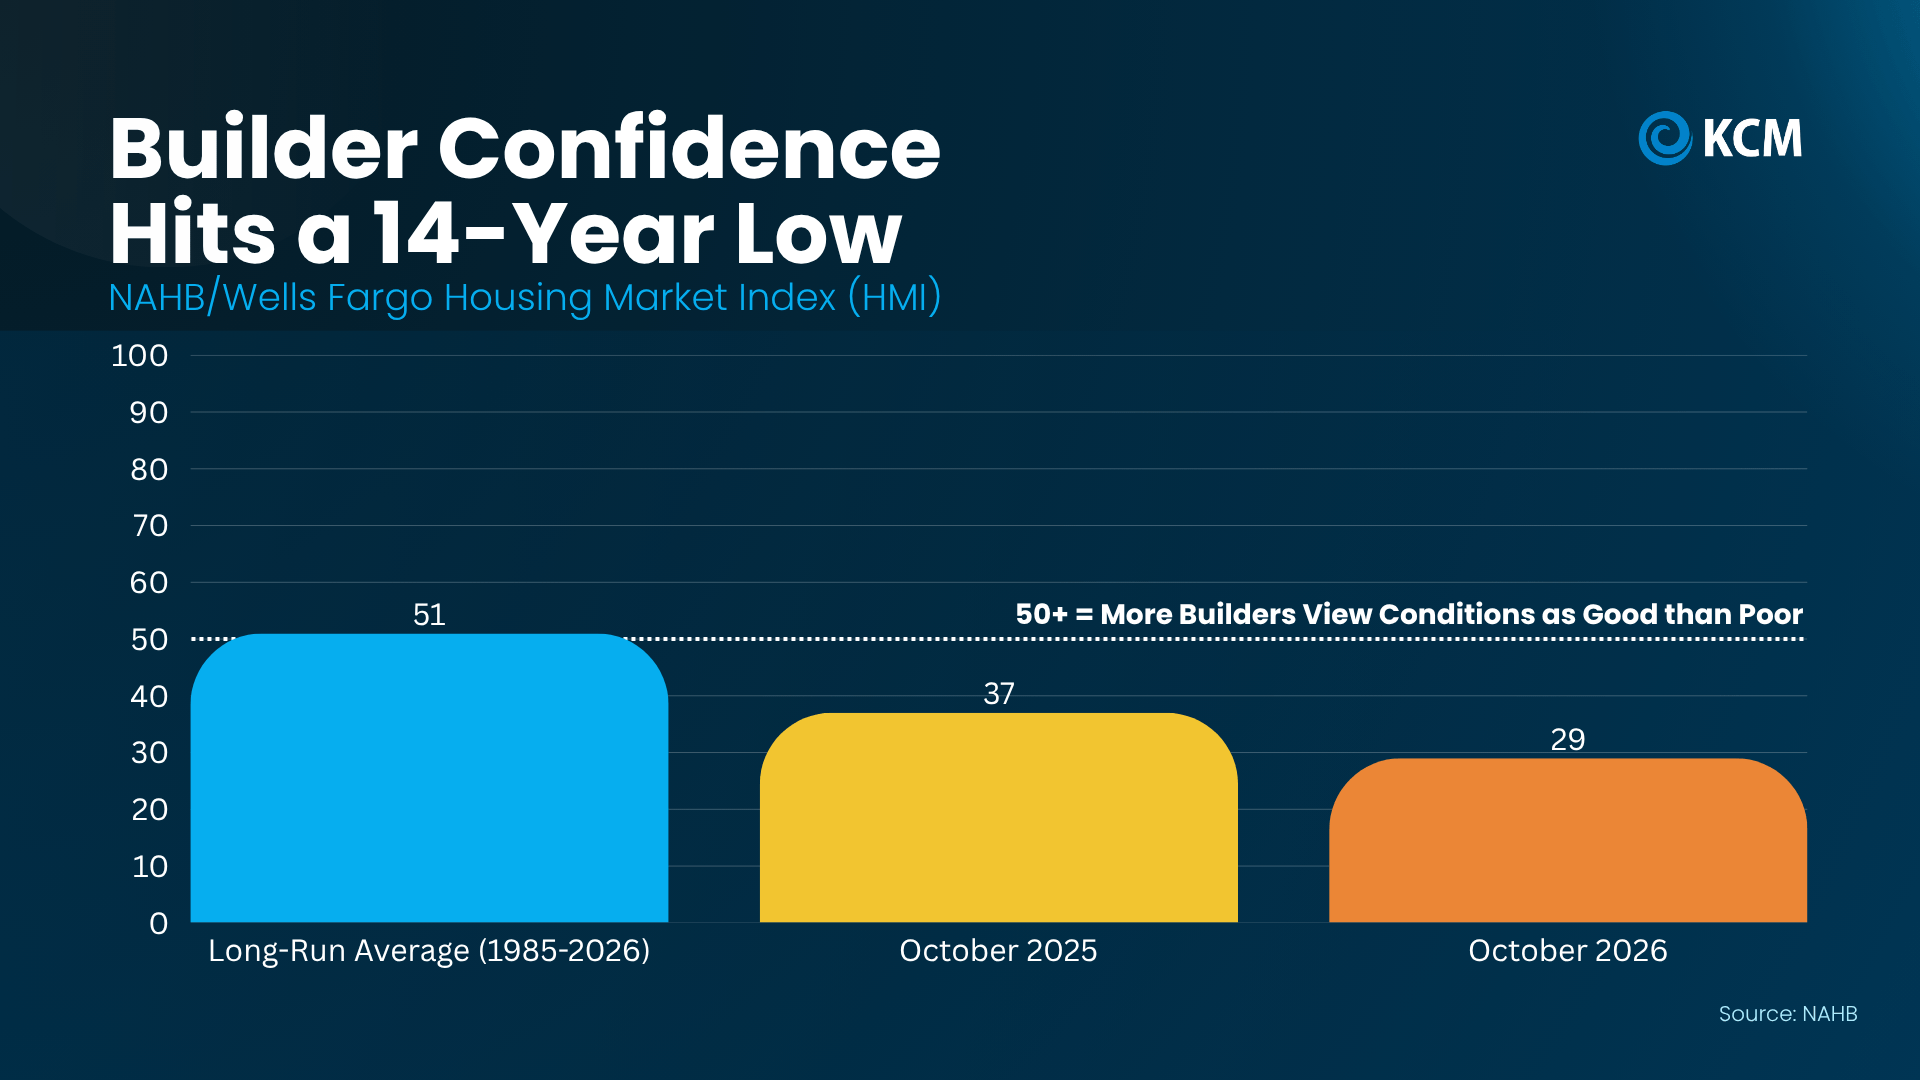
According to the National Association of Home Builders (NAHB), builder confidence dropped to 29 in October, its lowest level since June 2012. Traffic from prospective buyers also dropped to its lowest level in more than a decade, excluding the start of the pandemic.
As Robert Dietz, Chief Economist at NAHB, explains:
“Demand persists, but higher mortgage rates, elevated construction costs and weaker consumer confidence are keeping more buyers on the sidelines.”
Here’s why that matters for you.
A homeowner may be able to wait for the right offer. But a builder with several finished houses sitting unsold may have more reason to get those homes sold sooner rather than later.
And that means they may be more willing to work with you than you think.
Builders Are Already Making Moves To Win Buyers Over
If you’ve always assumed builders don’t negotiate, take a look at what they’re actually doing. According to the latest survey from NAHB, in October:
- 65% of builders are offering sales incentives.
- 43% are cutting prices, the highest share recorded between 2020 and 2026.
- And 6% is what they’re typically taking off the price.
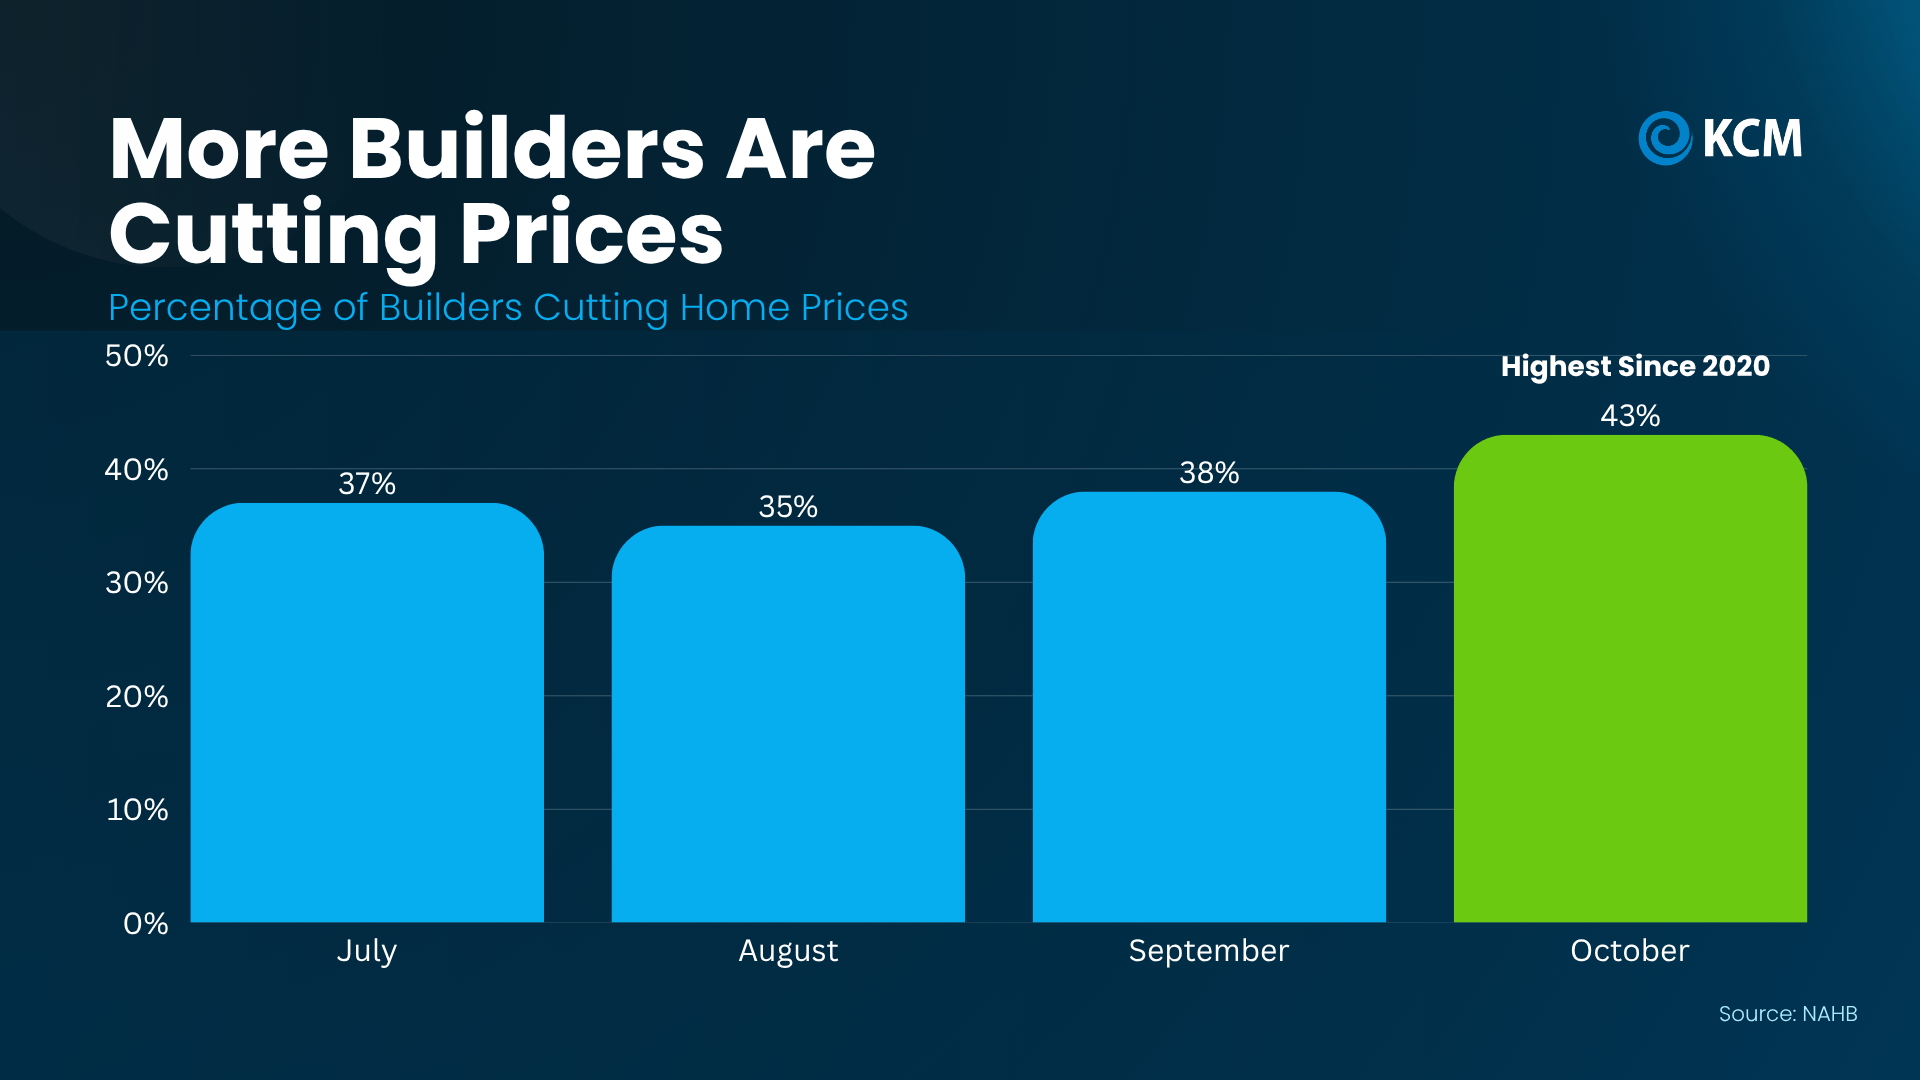
So, yes. Builders absolutely do negotiate. And with demand slowing, there’s good reason to explore just how flexible they may be right now.
That could mean asking for a lower price. But it could also mean asking for a mortgage-rate buydown, help with closing costs, or upgrades that would otherwise cost you extra.
And here’s a tip that could make a real difference.
Don’t just look at the newest communities or the prettiest model homes. Look for builders with completed houses that haven’t sold yet.
Those are sometimes called quick move-in homes or spec homes. And the longer one of those move-in ready homes sits unsold, the more reason a builder may have to consider an offer that helps get it off their books.
Don’t Just Ask What’s Available. Ask What’s Negotiable.
Don’t assume the advertised price or incentive package is the best they’ll do.
This is where having your own agent can really pay off. An agent who knows the local market can help you compare what builders are offering, identify communities with more available homes, and understand where there’s room to negotiate.
Of course, not every builder will offer the same incentives. And some may be more flexible on closing costs or mortgage rates than on the price itself.
But that’s exactly why it pays to ask.
The trick is knowing where to look, what to ask for, and how much room there may be to negotiate. And that’s where having your own agent is key.
Bottom Line
A homeowner who isn’t ready to accept a lower offer may be able to wait. But a builder with finished houses to sell has a different set of priorities. And that could work in your favor.
If you’re ready to buy, let’s look at which builders have completed homes sitting on the market in our area and see what they’re willing to offer to get them sold.
To Sell or Rent? How To Choose the Best Path for Your House.
Selling your house is a big step, and you want it to go smoothly. And with houses taking a little longer to sell these days, renting it out might start to sound like a nice backup plan.
But the reality is, while renting can work well for some people, it’s also a big commitment. So before you decide, it helps to see the whole picture first.
Why Some Sellers Are Deciding To Rent Instead
Lately, some sellers are choosing to hang on to their houses and rent them out instead. According to Parcl, around 9% of homes for rent right now were previously up for sale.
Here’s why.
Some homeowners put their houses on the market expecting a faster process than they got or a certain price buyers didn’t respond to. And when things didn’t go exactly as planned, they decided to rent instead. As Kara Ng, Senior Economist at Zillow, explains:
“Bargaining power is tilting toward buyers and homes are taking longer to sell, making renting out a property one way to buy time rather than compete aggressively on price.”
But here’s the important distinction. Just because some sellers are choosing to rent doesn’t mean selling isn’t working. In many cases, the difference comes down to how well a house is priced, prepared, and marketed for today’s buyers.
Parcl data shows where these “accidental landlords” – owners who planned to sell but decided to rent instead – are most common (see graph below):
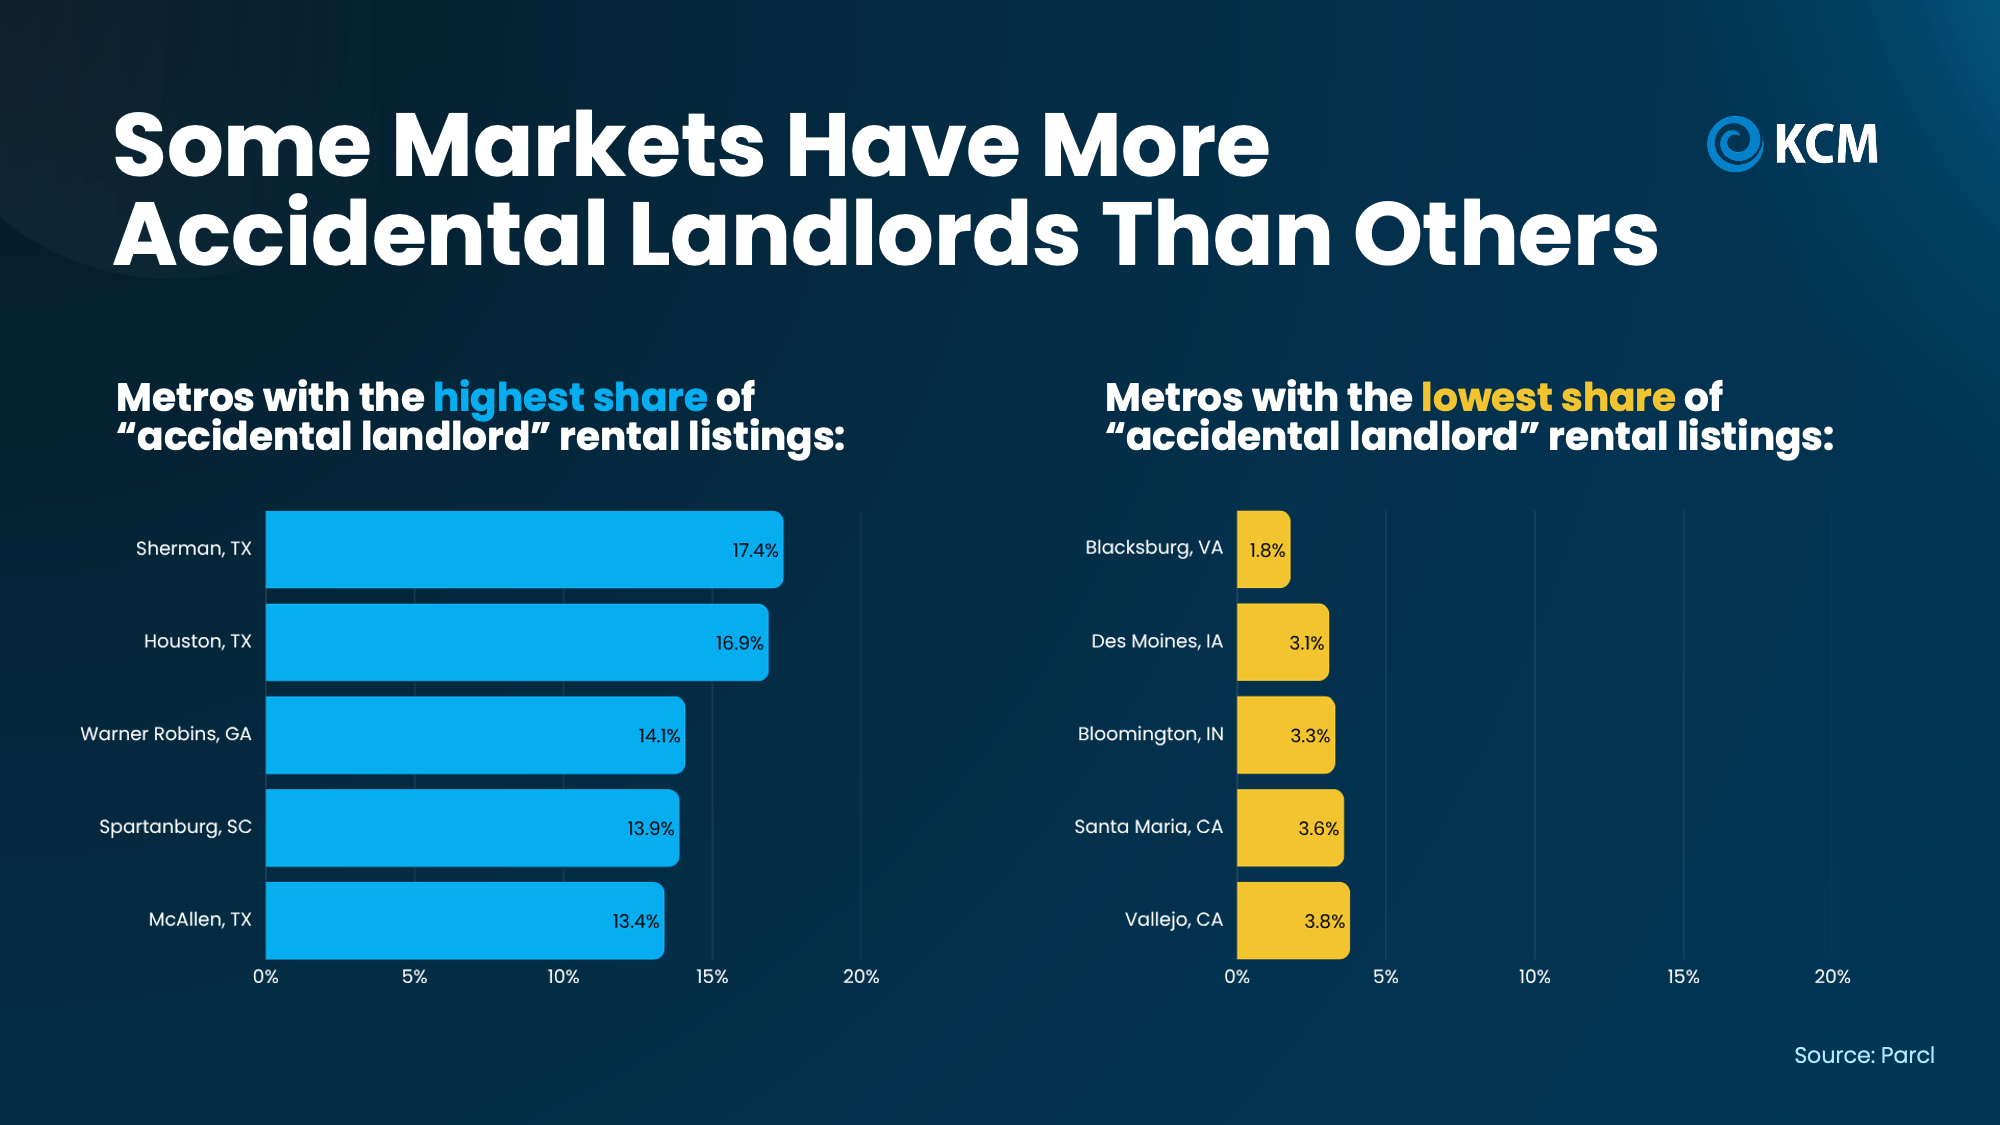
They make up around 17% of homes for rent in places like Sherman and Houston, TX, but less than 4% in markets like Des Moines, IA and Bloomington, IN.
That’s a pretty big difference. And it shows why you have to know what’s happening in your neighborhood. Your market, your asking price, and your strategy all play a role in how your sale goes.
A local agent can show you how houses like yours are selling, what strategies work best, and help you weigh your options – not to push you to sell, but so you at least have the full picture based on today’s market. And part of making an informed decision is understanding what renting your house would actually take.
What Being a Landlord Actually Looks Like
While renting might sound like easy passive income on paper, in practice, it’s a hands-on job with rules to follow. As Invest West Management puts it:
“Even if you never intended to become a landlord, the law still sees you as one — and you must meet all legal obligations that come with that role. This often includes registering the tenancy, providing tenants with certain disclosures, and ensuring the property meets safety standards.”
You’d also be the one chasing missed rent payments, fixing damage between tenants, and covering unexpected repairs. Not to mention fielding weekend calls about leaky dishwashers or broken AC units.
There are expenses beyond regular maintenance and repairs, too. According to Bankrate, these are a few of the biggest:
- Insurance premiums (landlord insurance typically costs about 25% more than a standard homeowners policy)
- Management fees (if you hire a property manager, they usually charge around 10% of the rent)
- Gaps between tenants, when you pay the mortgage without rental income
How To Give Your House a Strong Start
If you want to be a landlord and you’re prepared for the responsibility, renting may be a great fit. But if you’d really rather sell, don’t let today’s market convince you that you can’t.
A great agent can make it happen. The key is having an open conversation up front with your agent about pricing and how to market your house. Nailing those details from day 1 helps your house make a great first impression, so renting doesn’t have to be your fallback.
Bottom Line
Renting can be a good fit for the right person with the right house, but it isn’t the only option. A smart sales strategy can help your house stand out to buyers from day one.
So, if you’re on the fence, let’s sit down and compare what selling and renting would each look like for you.
Confused by Home Price Headlines? Here’s Why.
Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.
One says home prices are falling. The next says they’re still climbing.
So, which one’s right? It comes down to where you live.
What’s Really Going on with Asking Prices
Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.
Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.
According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):
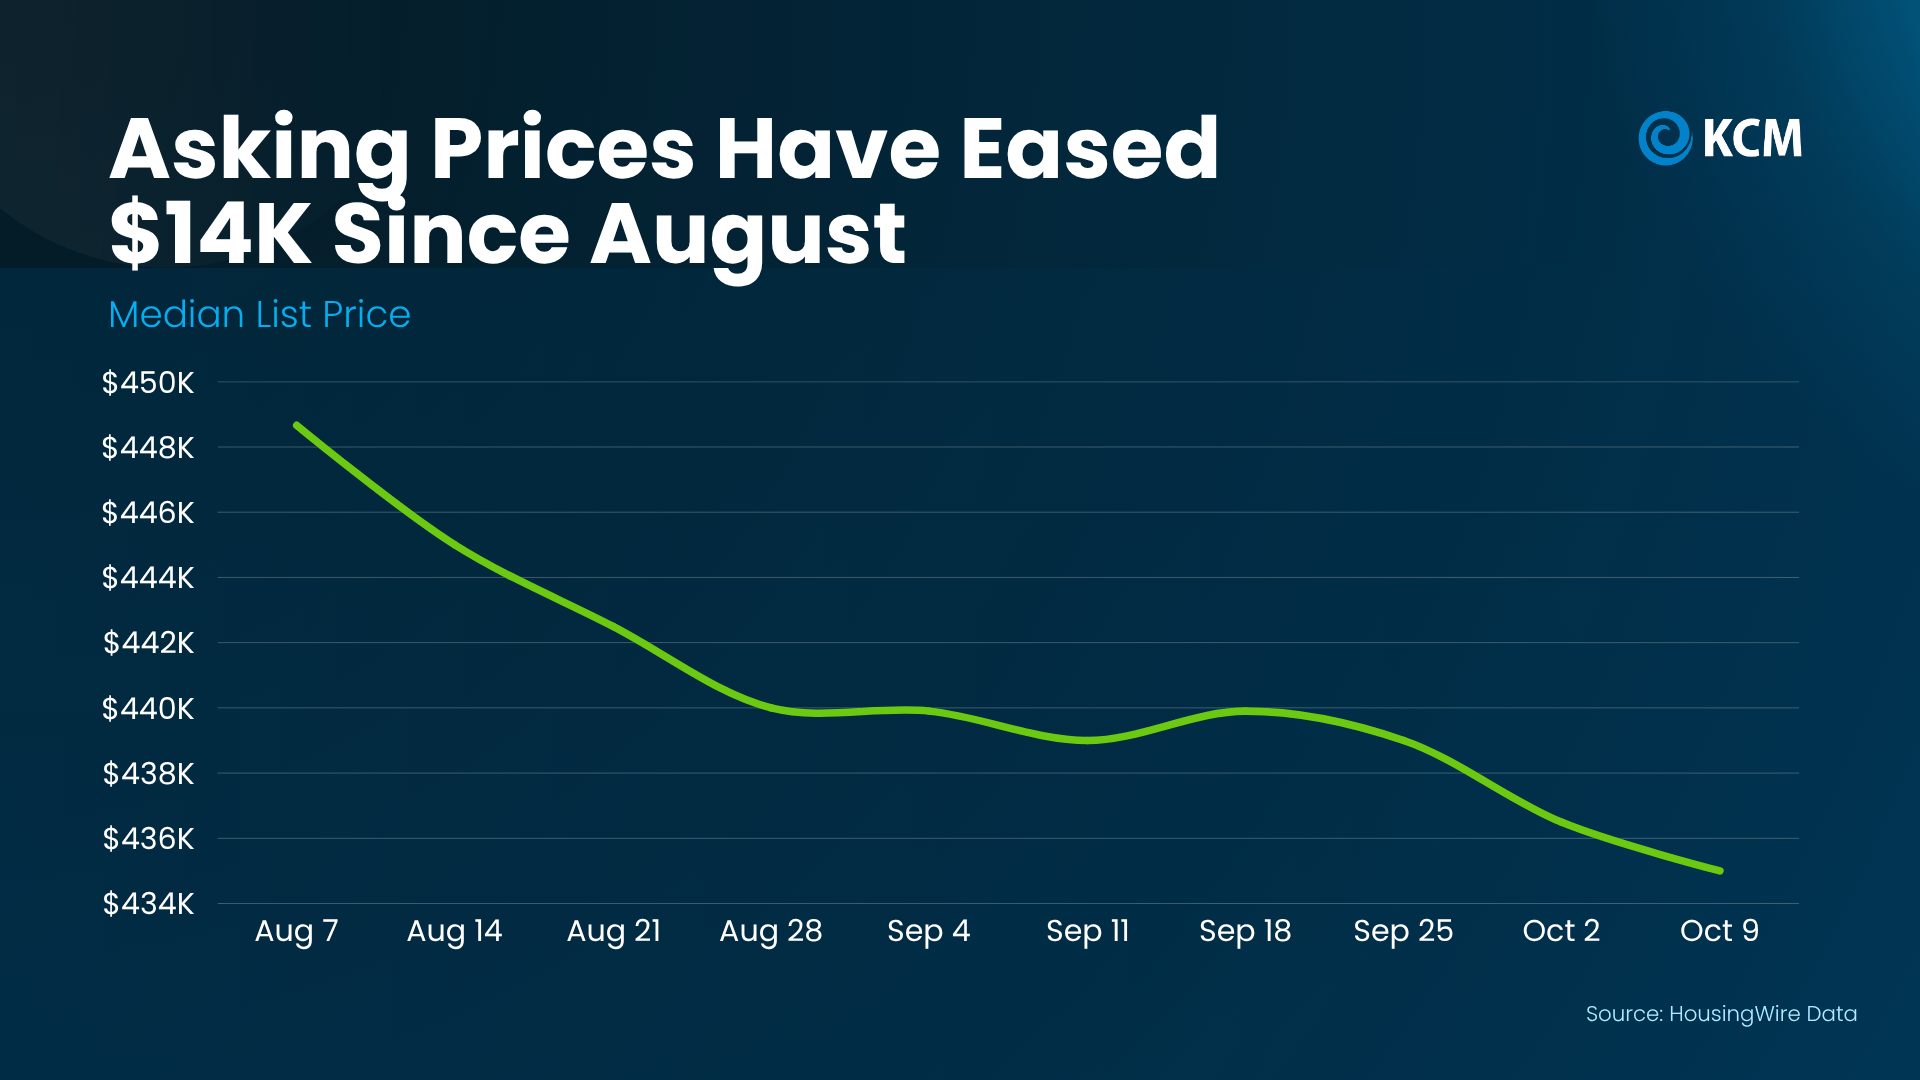
That’s a dip of about 3%, and a lot of it is normal for this time of year.
Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.
Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.
Where You Live Changes Everything
Realtor.com explains:
“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):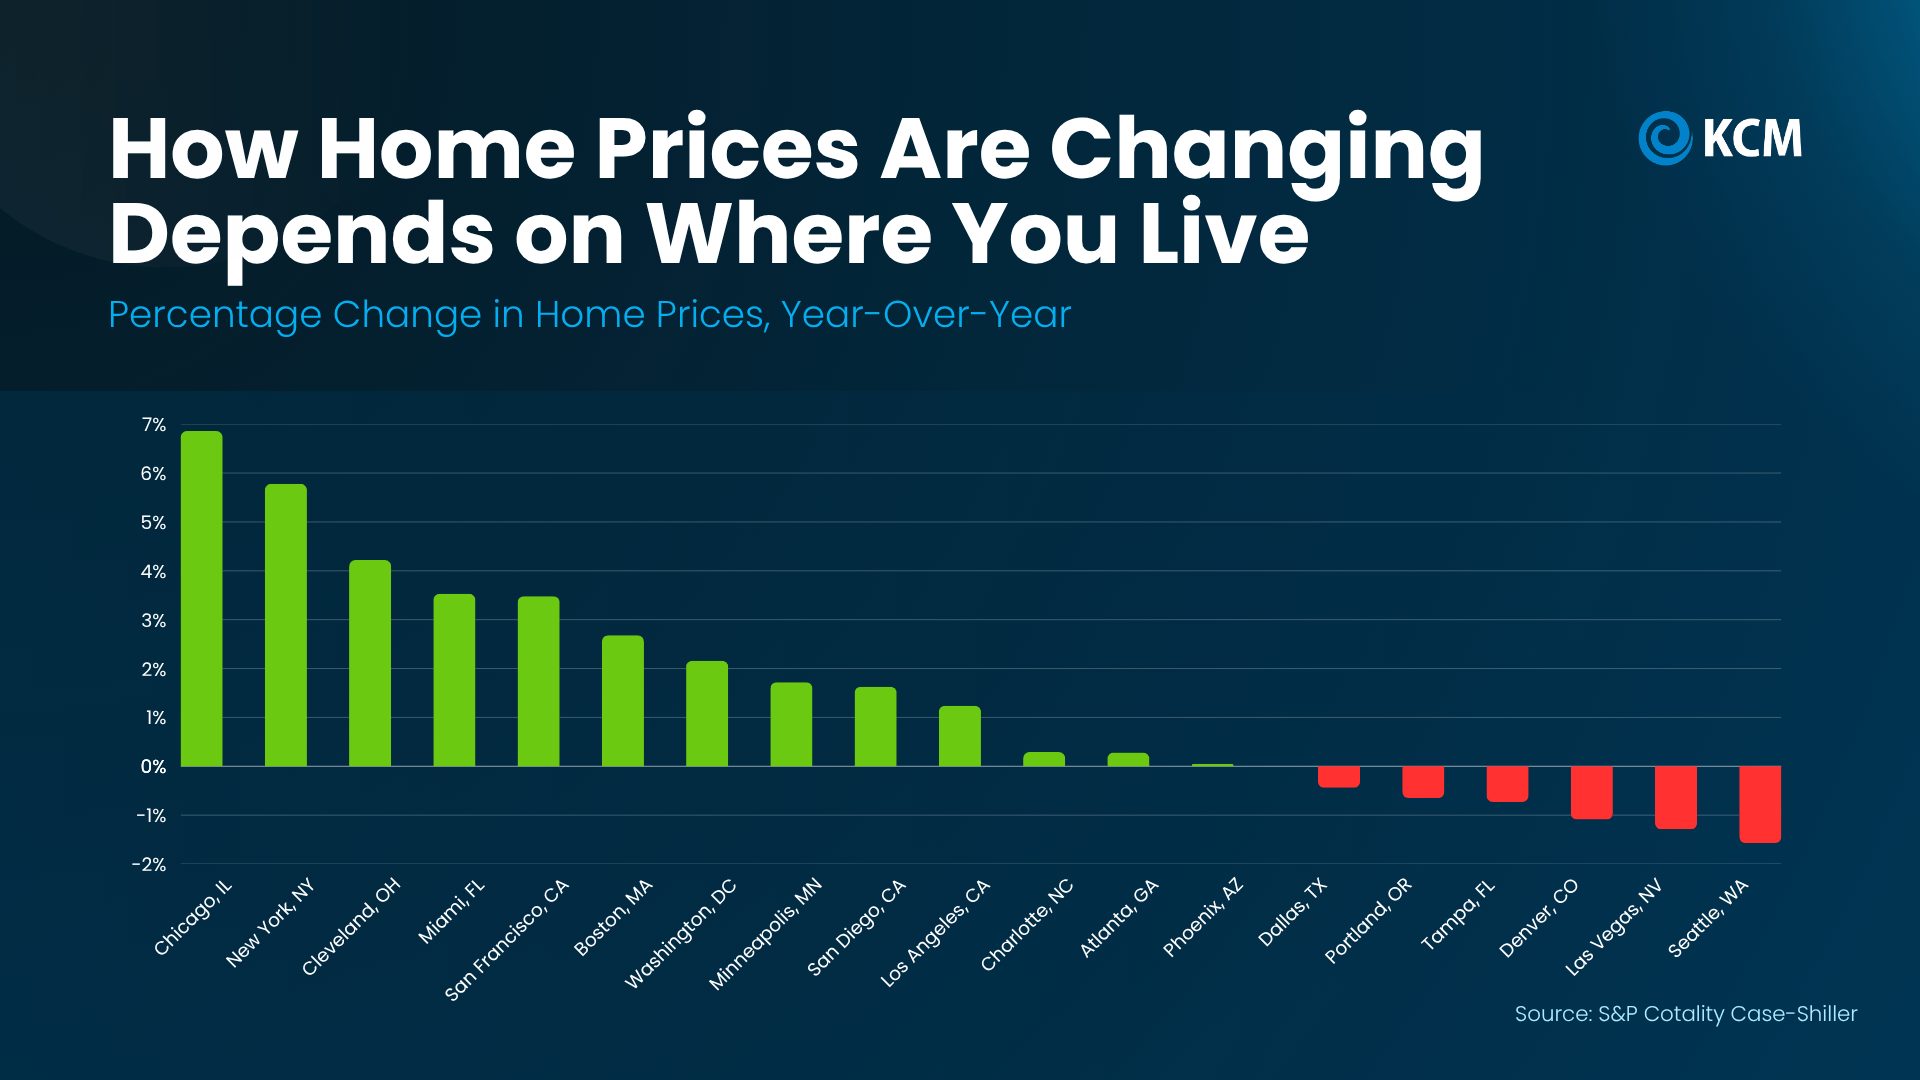
That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.
Why You Don’t Need To Worry About a Crash
Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.
And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):
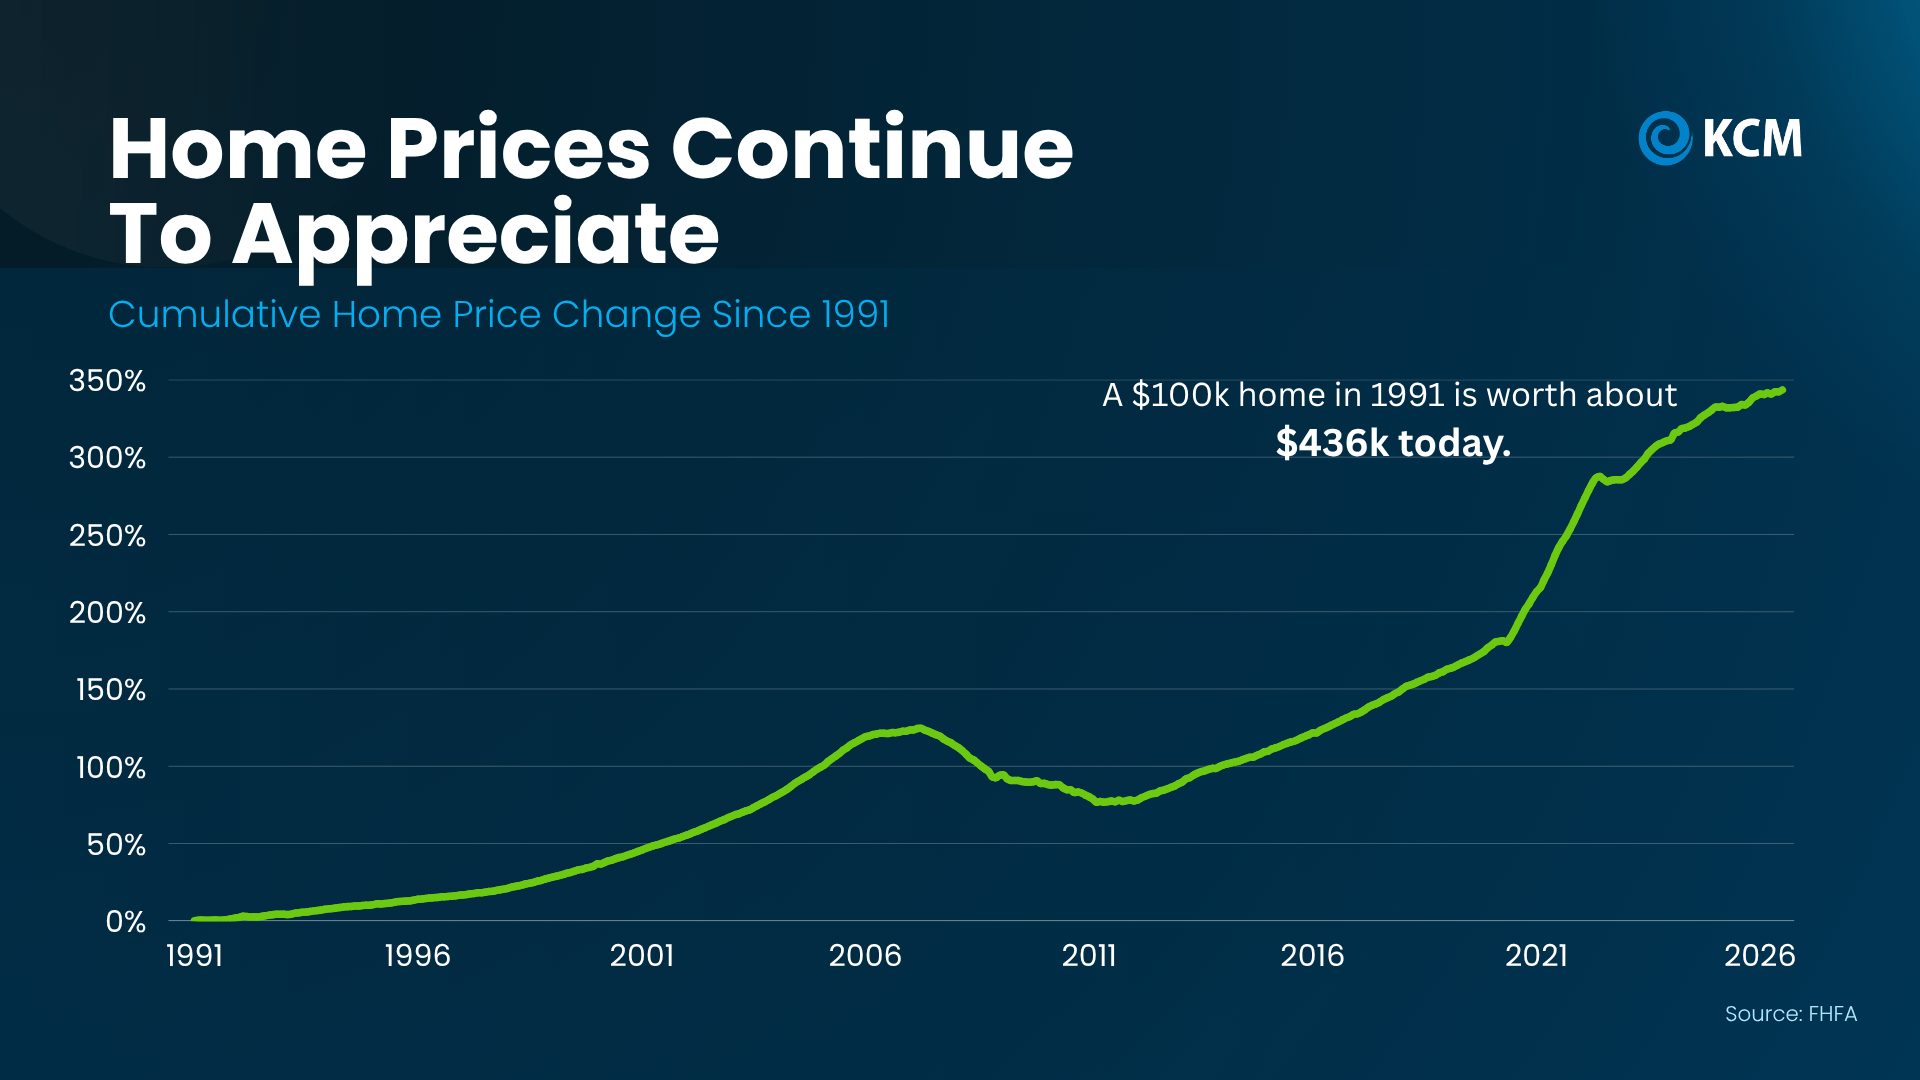
So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.
Bottom Line
National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, let’s look at how prices are moving in your area, so you can set your price or make your offer with confidence.
Why There are More Homes for Sale Right Now (and What It Means for You)
Mortgage rates being back above 7% isn’t exactly the news most people wanted. But it’s changing the market in ways that matter whether you’re buying or selling.
The number of homes for sale is growing faster than it was this time last year. And interestingly, the main reason isn’t a flood of new listings. It’s because homes aren’t selling as quickly.
Here’s why – and what that means if you’re thinking about buying or selling.
Inventory Growth Is Picking Up Steam
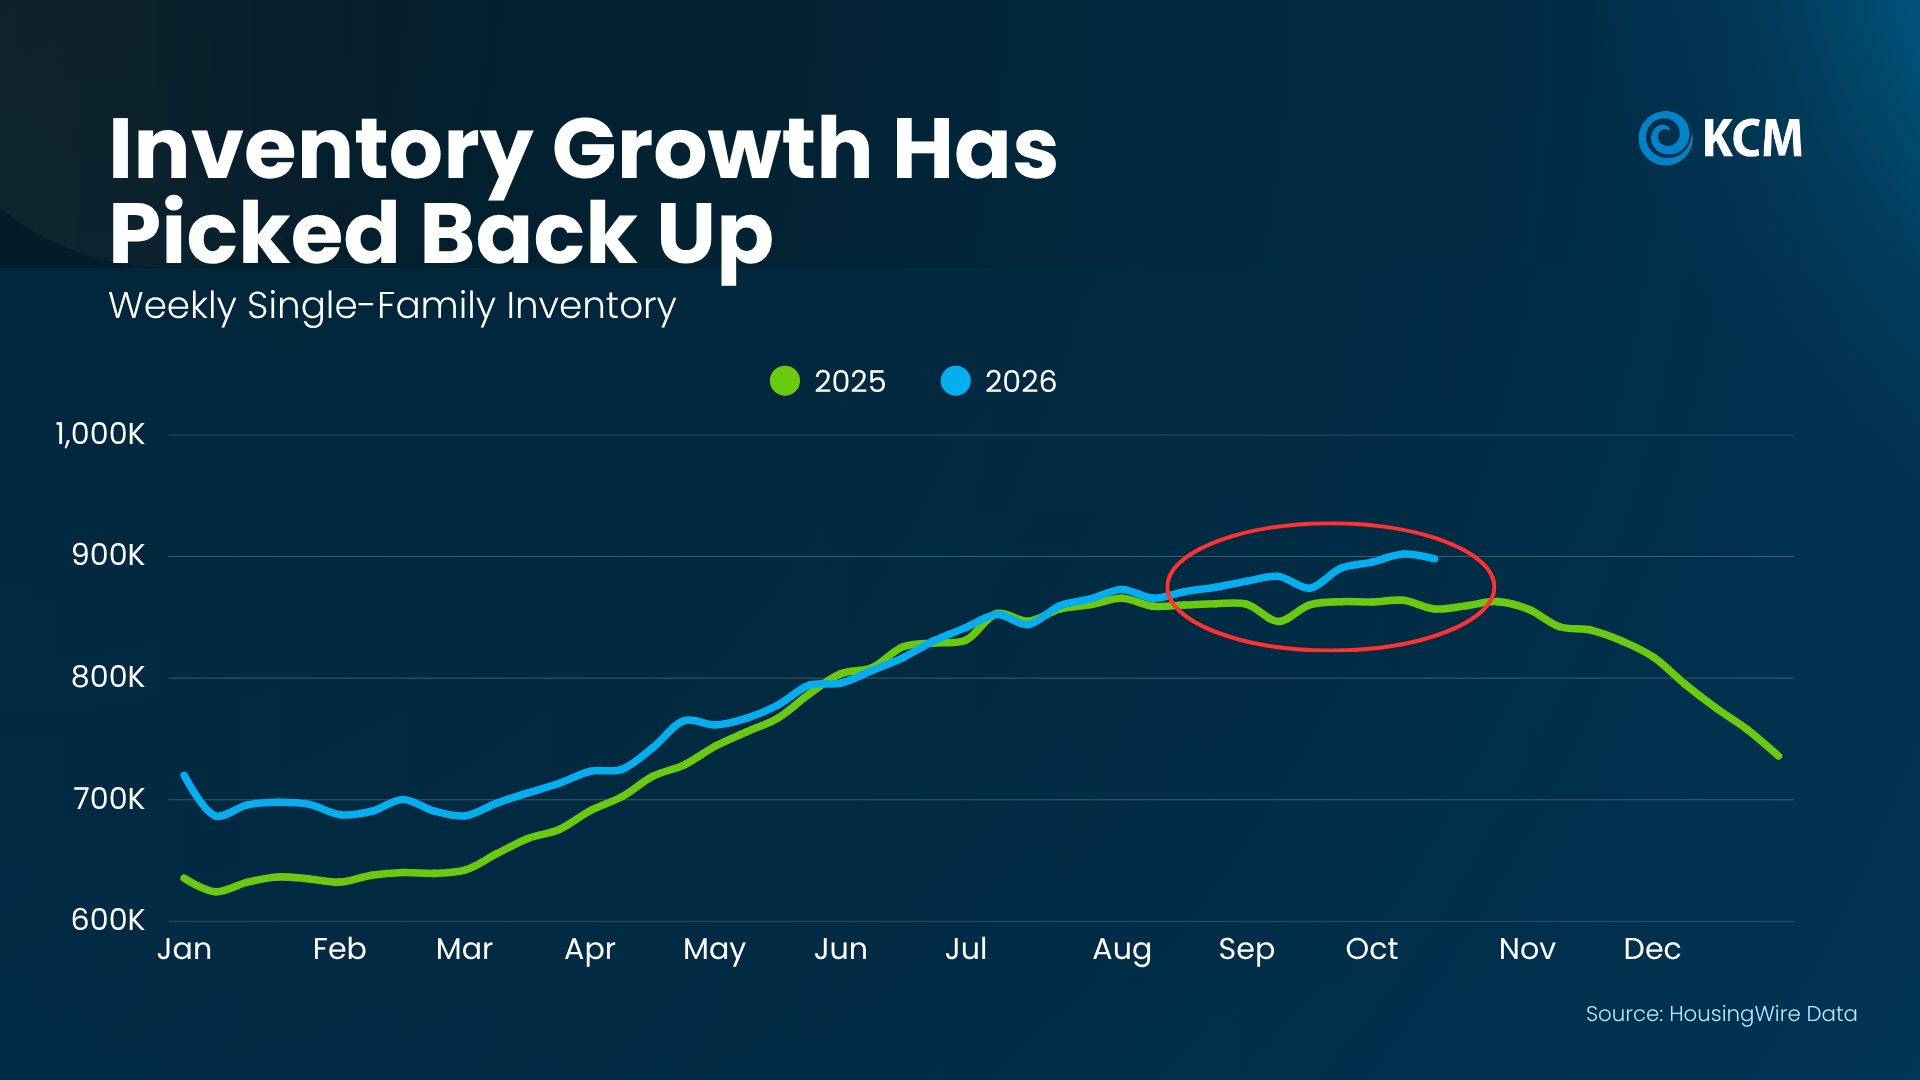
According to HousingWire Data, after inventory growth slowed down for most of the past year, it’s accelerated again in recent weeks. You can see that in the graph below. Just look at the blue line:
And what’s behind this shift might surprise you.
When rates rise, some buyers hit pause. That means fewer homes sell each week. And as those unsold homes stay on the market alongside new listings, the number available starts to grow (see the blue line in the graph below).
Here’s another way to look at it to make it even more obvious. The graph below shows the relationship between rates and inventory. Again, this year is the blue line. Last year? That’s the green.
With rates inching up this year, you can see inventory has grown by about 25k. But when rates went down this time last year, buyers jumped back in, and inventory actually dropped by about 9k.
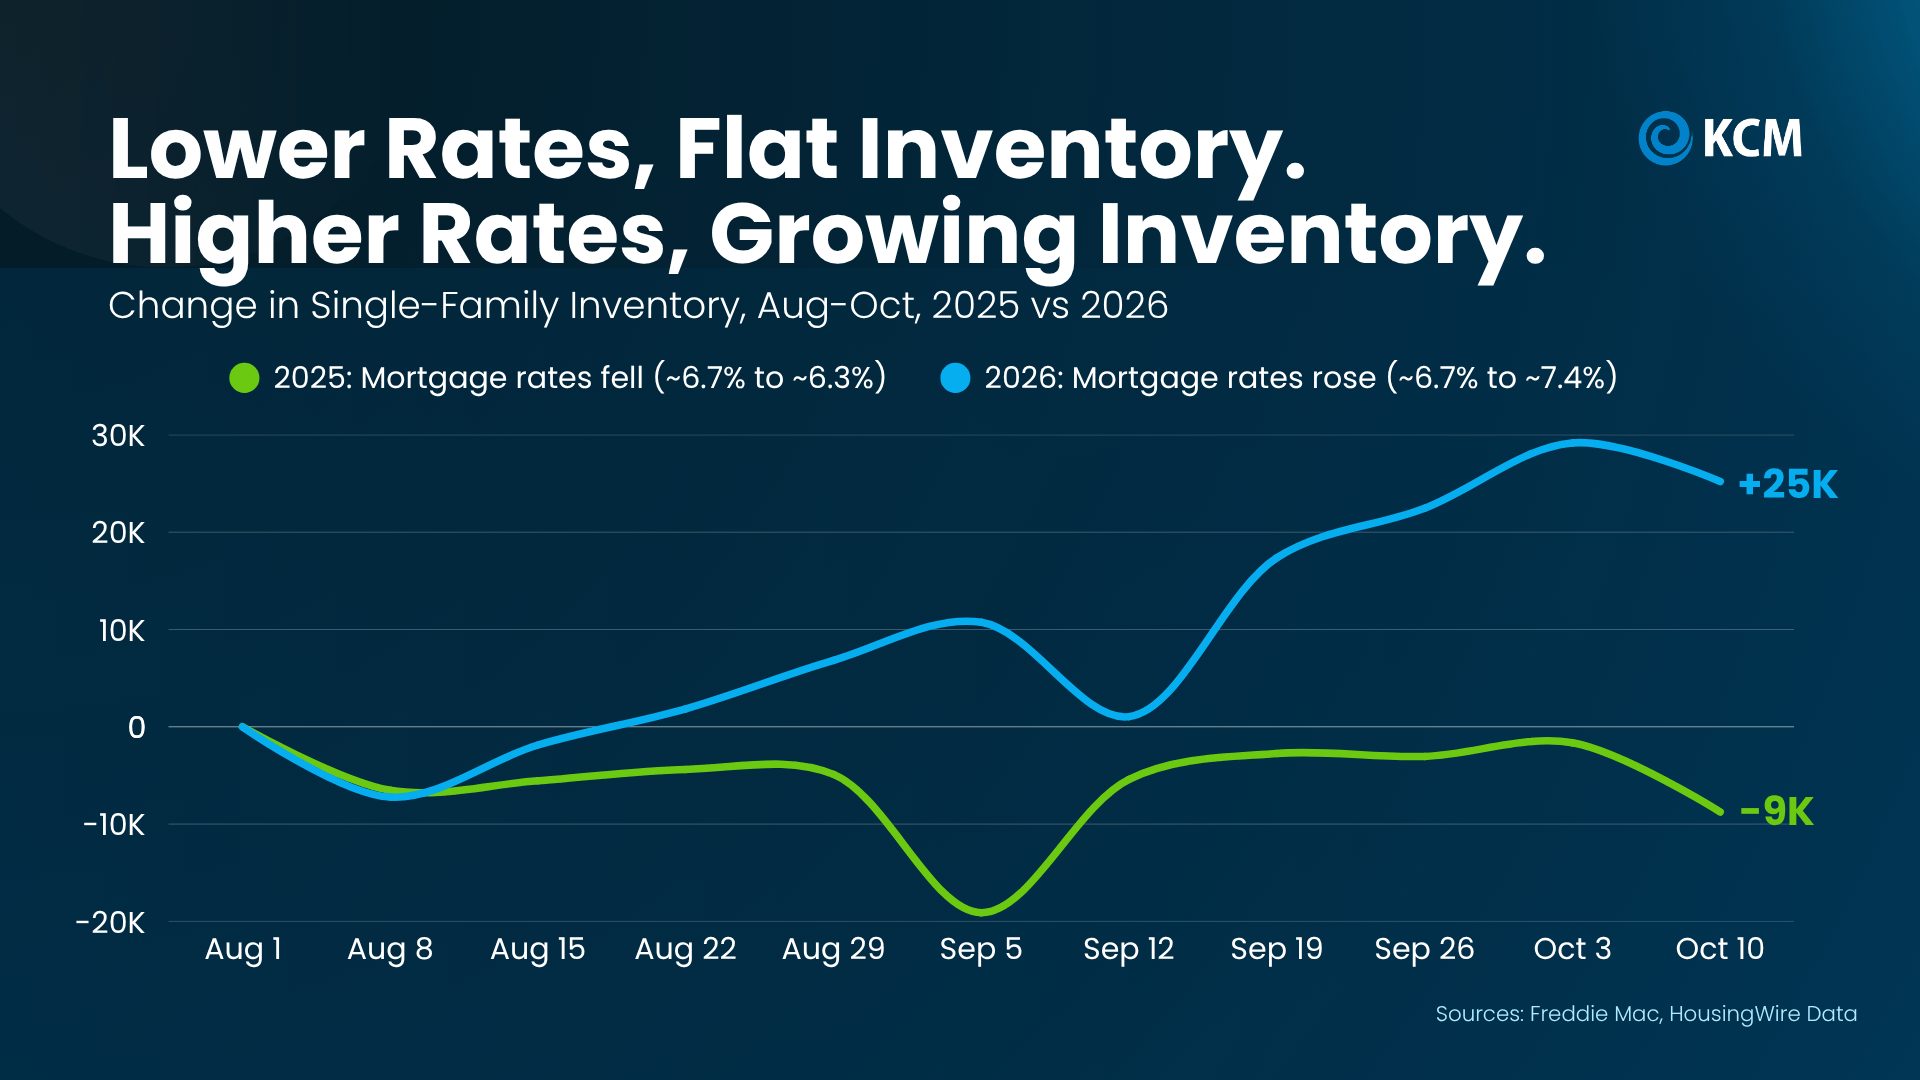
Logan Mohtashami, Lead Analyst at HousingWire, explains how that’s flipped from 2025 to 2026:
“With mortgage rates over 7%, demand tends to soften and inventory rises . . .”
Homes Are Spending More Time on the Market
Here’s another metric that shows the impact rates are having: time on market. Data from Realtor.com shows the typical home spent 61 days on the market this September. Back in September 2021, it was just 41 days (see graph below):
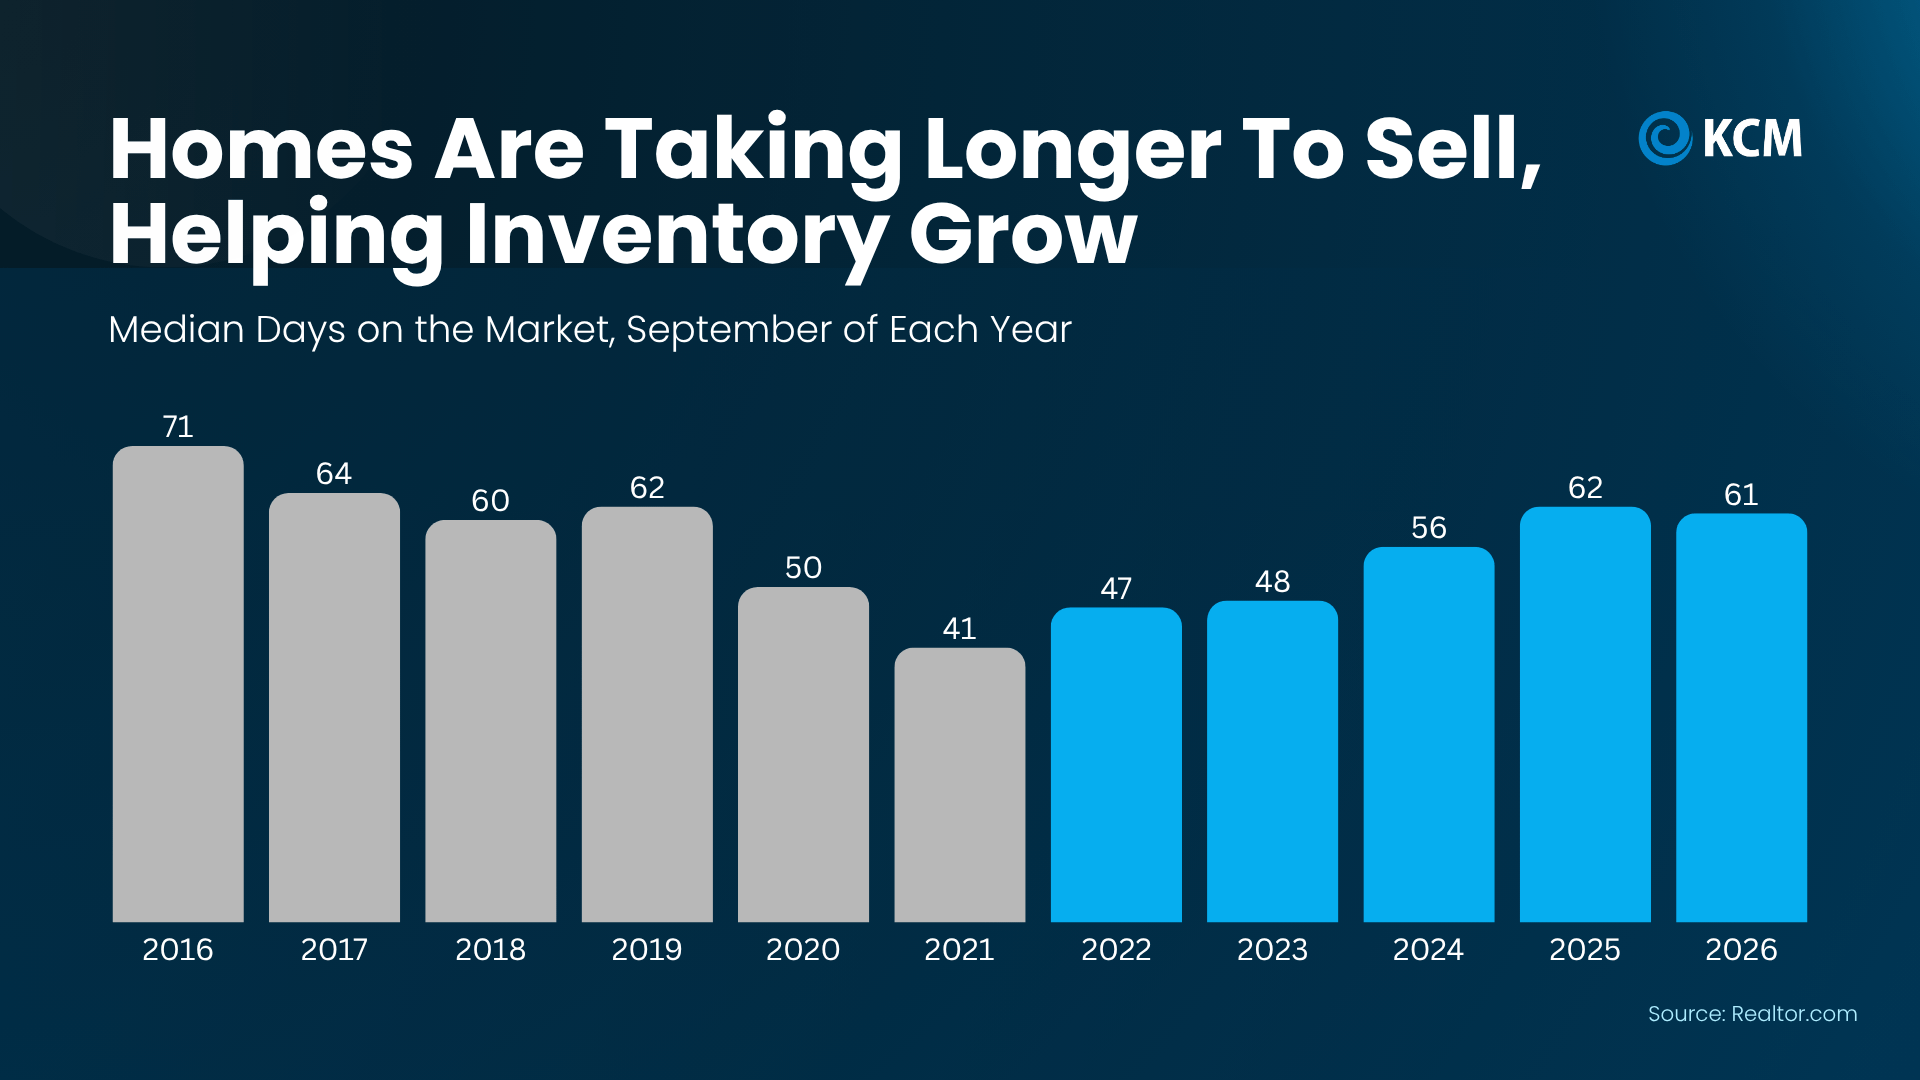
Here’s what that tells us. In 2021, when rates were low, more buyers were active, and homes sold fast. But now that rates are a bit higher, not as many buyers are interested, so it takes a bit longer to close a deal.
How To Make This Market Work for You
So, what does all of this mean for your plans? That depends on which side of the move you’re on:
If you’re buying, more homes for sale means more choices and less pressure to rush. And more room to negotiate too. A house that’s been sitting for a while could have a seller who’s more willing to talk – not just about price, but repairs, closing costs, or even helping buy down your mortgage rate.
That doesn’t mean every seller will play ball. But compared to the frenzy of a few years ago, buyers have more leverage now.
If you’re selling, the right strategy can make all the difference. Buyers have more homes to choose from, so making yours stand out is especially important. That starts with pricing it right from day one, making a great first impression, and working with your agent to highlight what makes your house worth choosing. Buyers are still buying and homes are still selling. The key is making sure yours is positioned to attract the right buyer.
The market hasn’t stopped. It’s just moving at a different pace. And whether you’re buying or selling, your strategy needs to move with it.
Bottom Line
In many places right now, inventory is growing and homes are taking a bit longer to sell. And that’s information that should shape the strategy you use going in.
Whether you’re buying or selling, let’s look at how long homes are taking to sell in your neighborhood, so your offer, or your price, fits today’s market.
Why Most People Are Still Glad They Bought a Home
With everything going on, it’s understandable if you’re wondering if you’d regret buying right now.
Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help…
Most people who already made that leap would do it again.
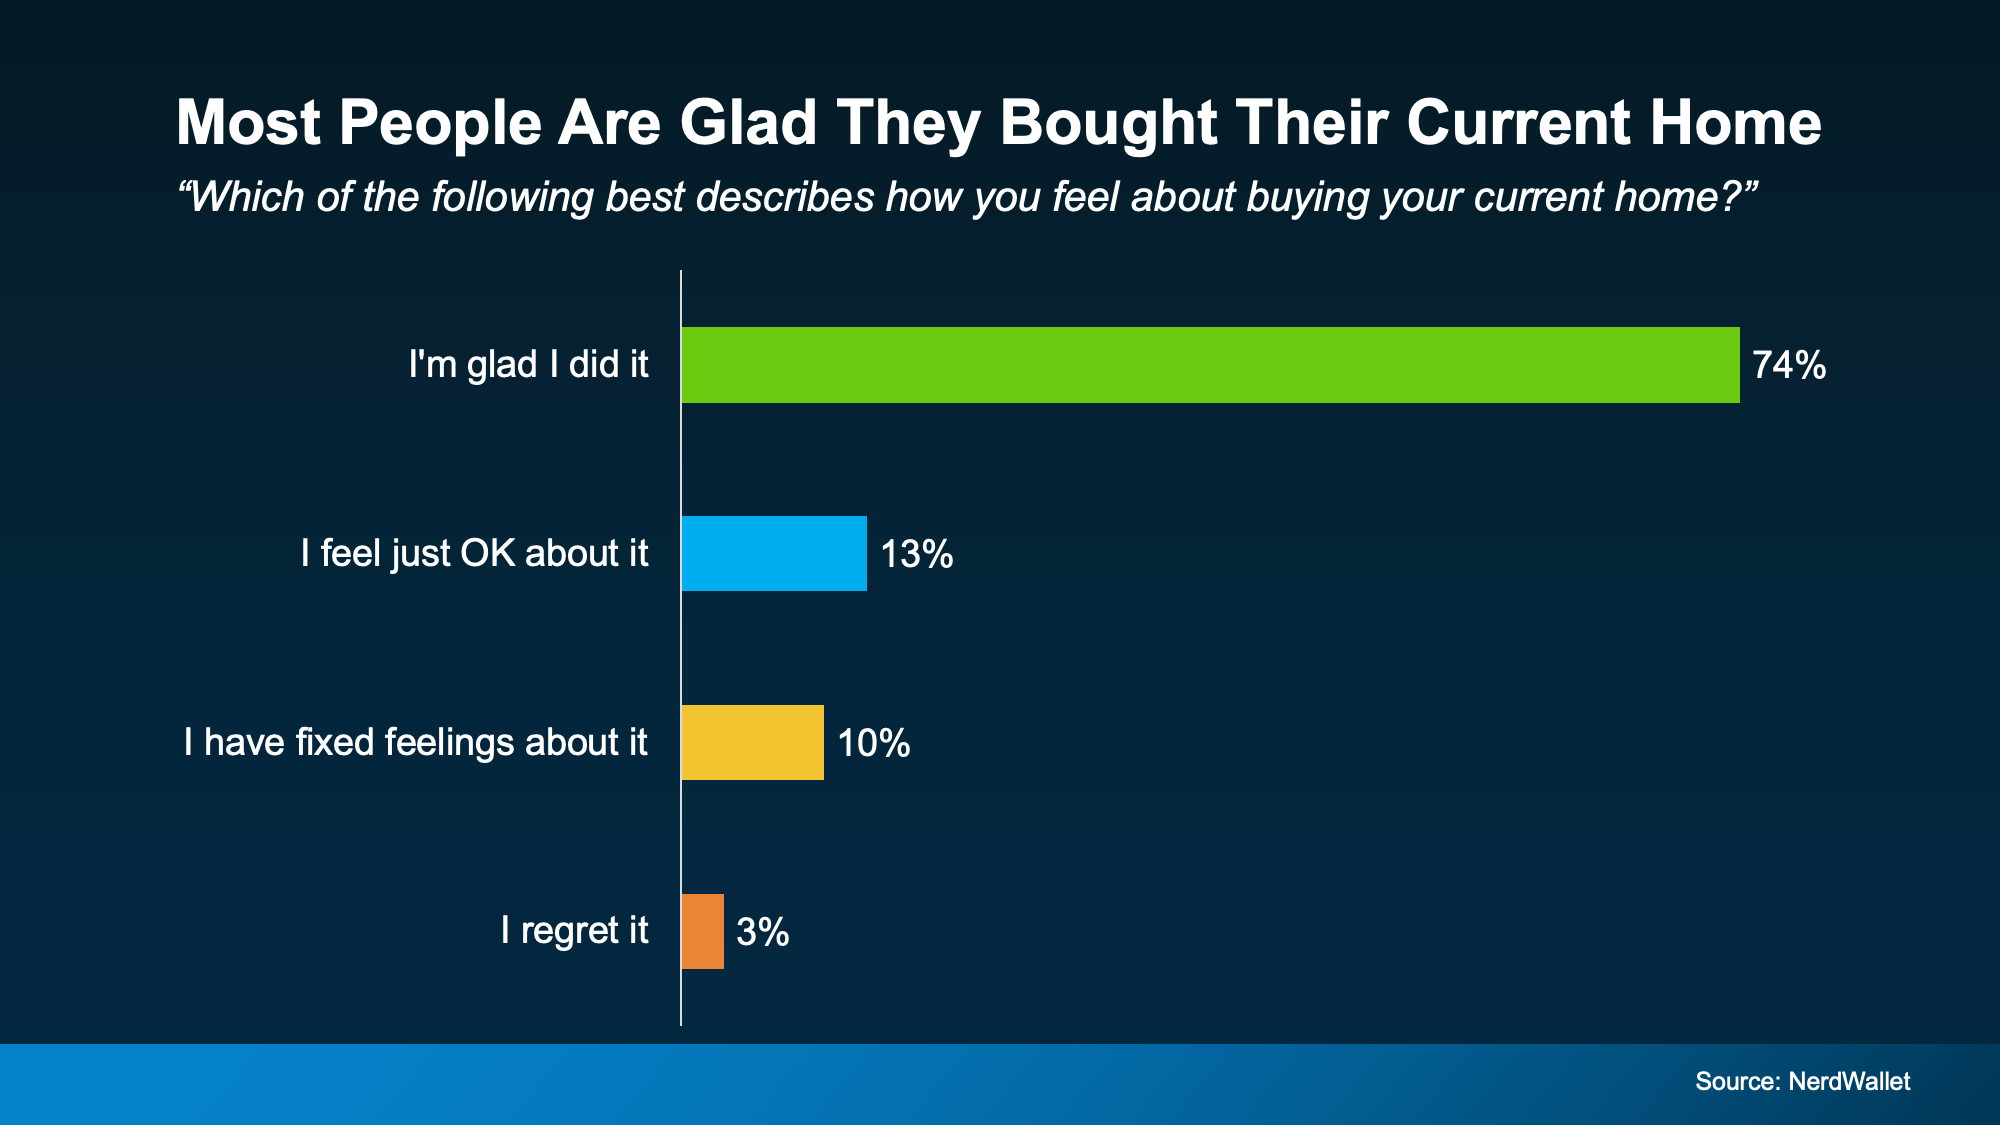
According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it:
And here’s a big reason why so many people feel it was worth it, even now.
Homeownership Is a Long-Term Play
When you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture.
A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity.
According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below):
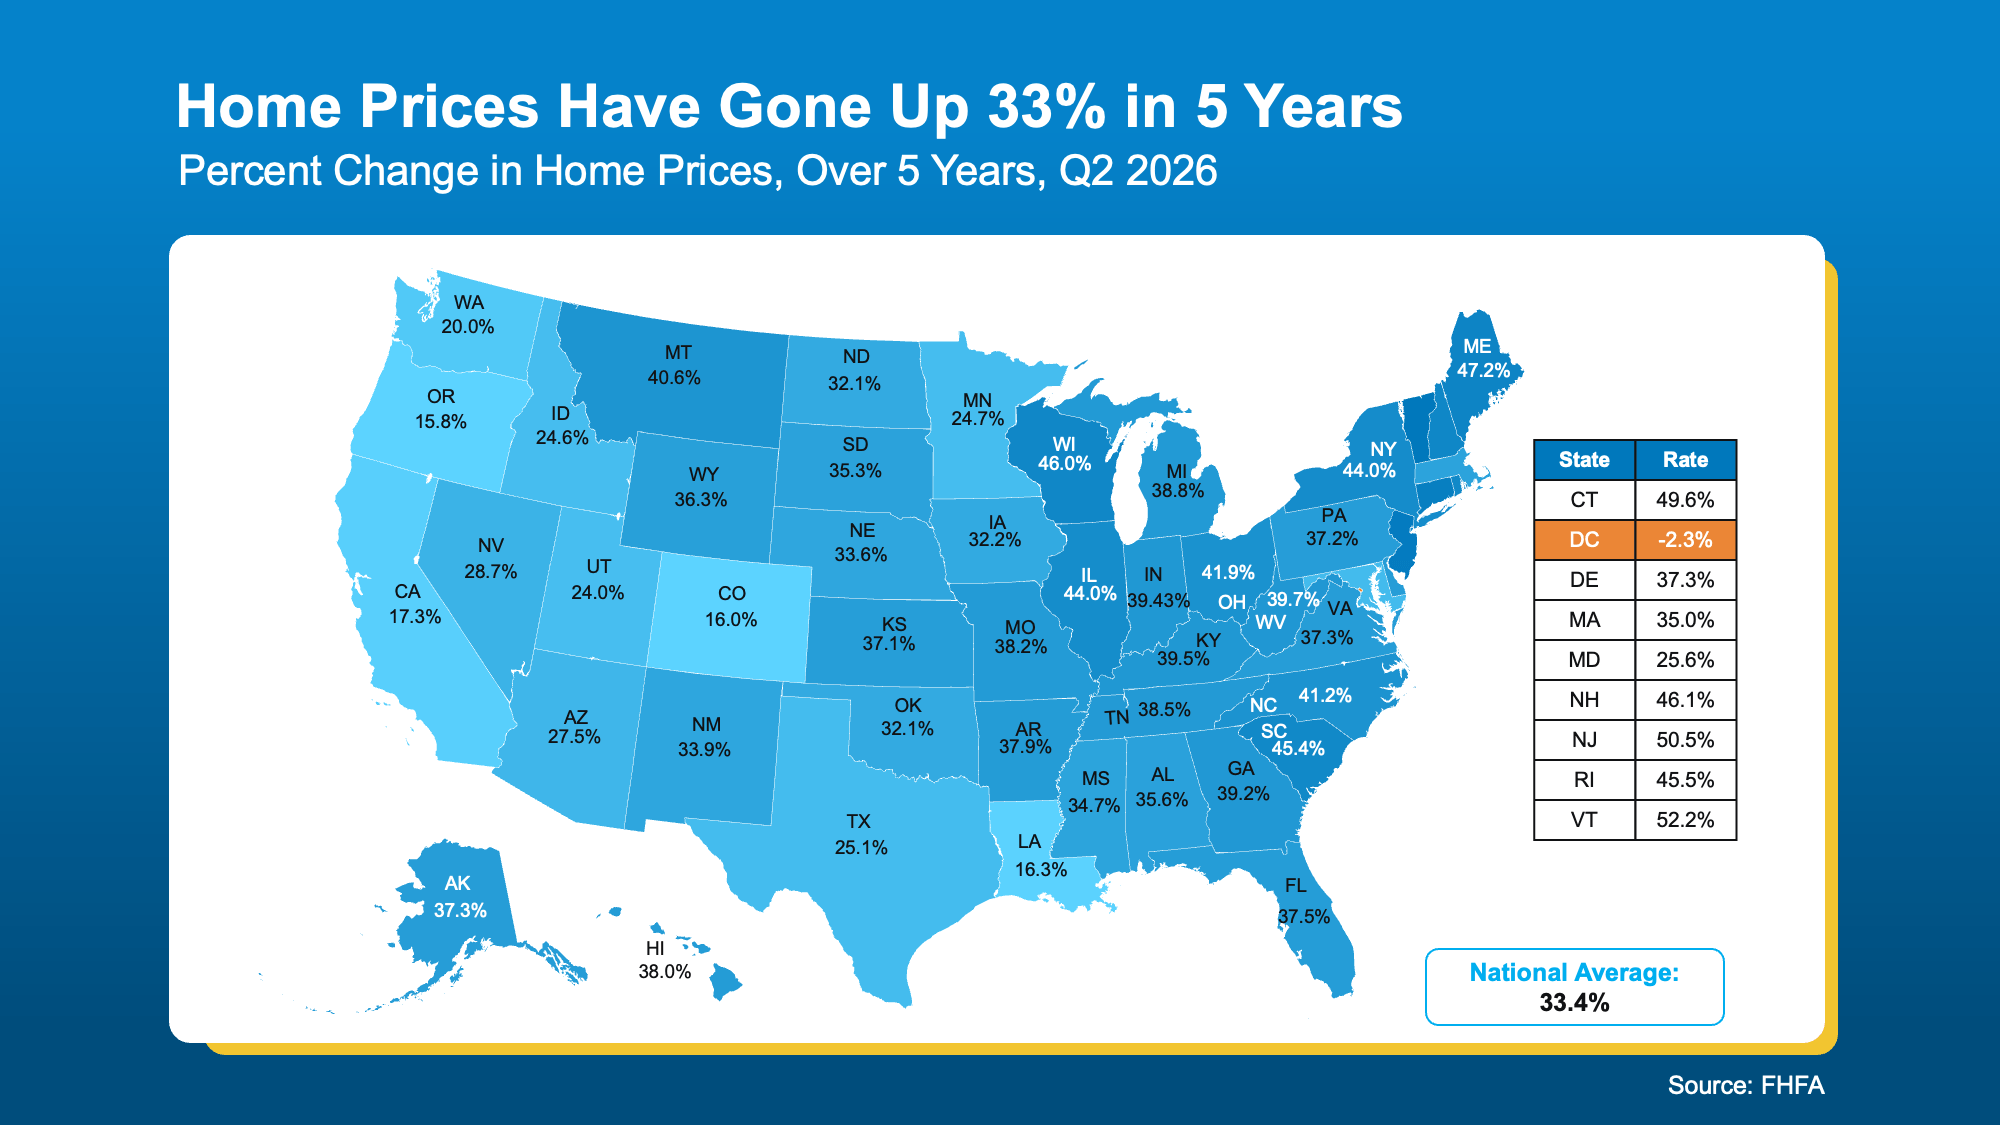
And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas.
That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow.
Now, Zoom Out Even Further
The five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles.
FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):
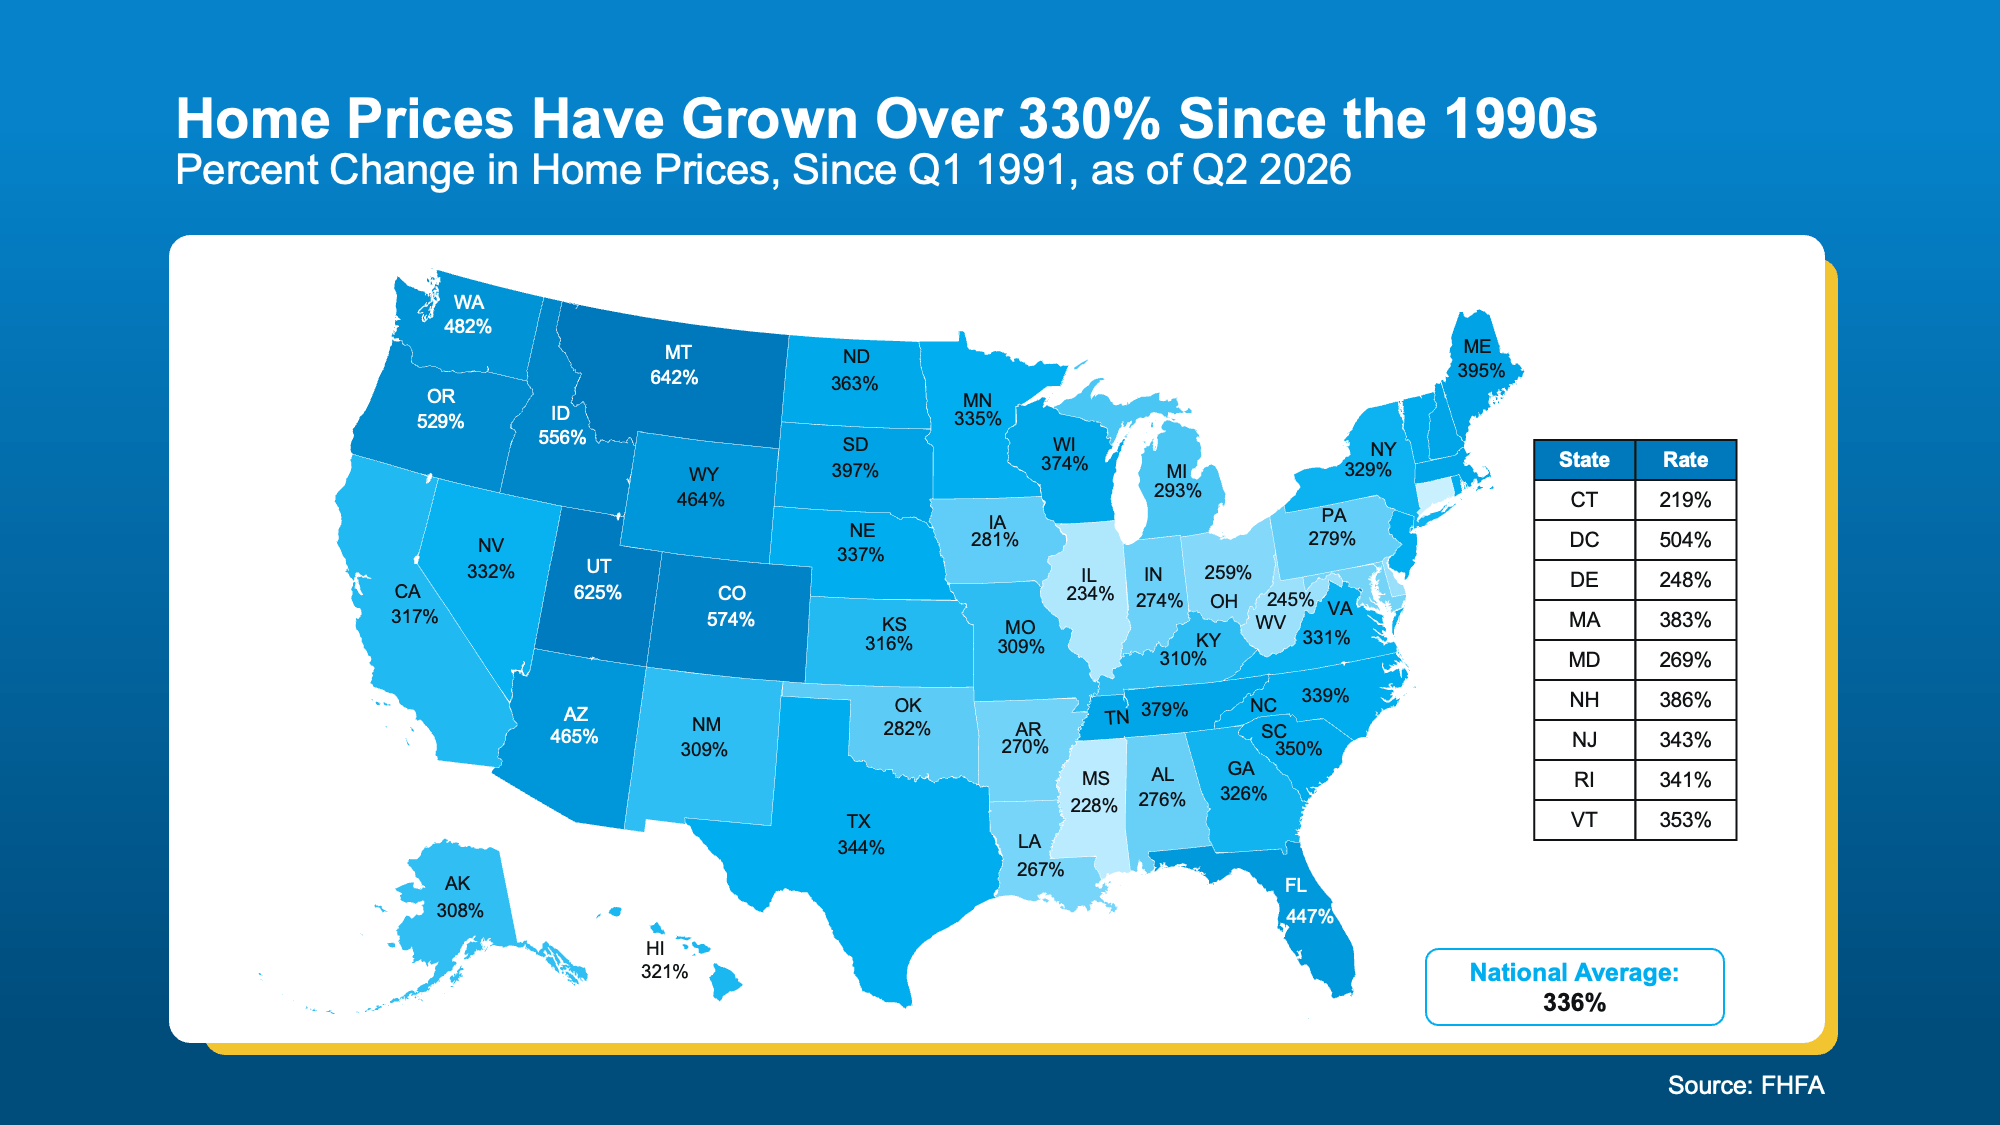
That doesn’t mean prices go up every single year. And it doesn’t mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you.
What it does show is why trying to perfectly time the market can make you miss the bigger picture.
Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains:
“Your home’s equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . .
If it’s time to upsize or downsize, you can use that cash for the down payment on your next home.”
Basically, if you can afford to do it, buying a home now could set you up for future moves.
And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year.
Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity.
Bottom Line
Don’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why.
If you’re wondering whether buying makes sense for you right now, let’s look at the numbers together – and what owning a home could mean for you in the years ahead.
Renovate or Relocate? What To Know Before You Decide To Age in Place
You’ve spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it’s natural to wonder if this is still the place you want to spend it.
Whether you’re leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here’s what to consider before you decide.
What It Can Take To Stay Put
Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier.
In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below):
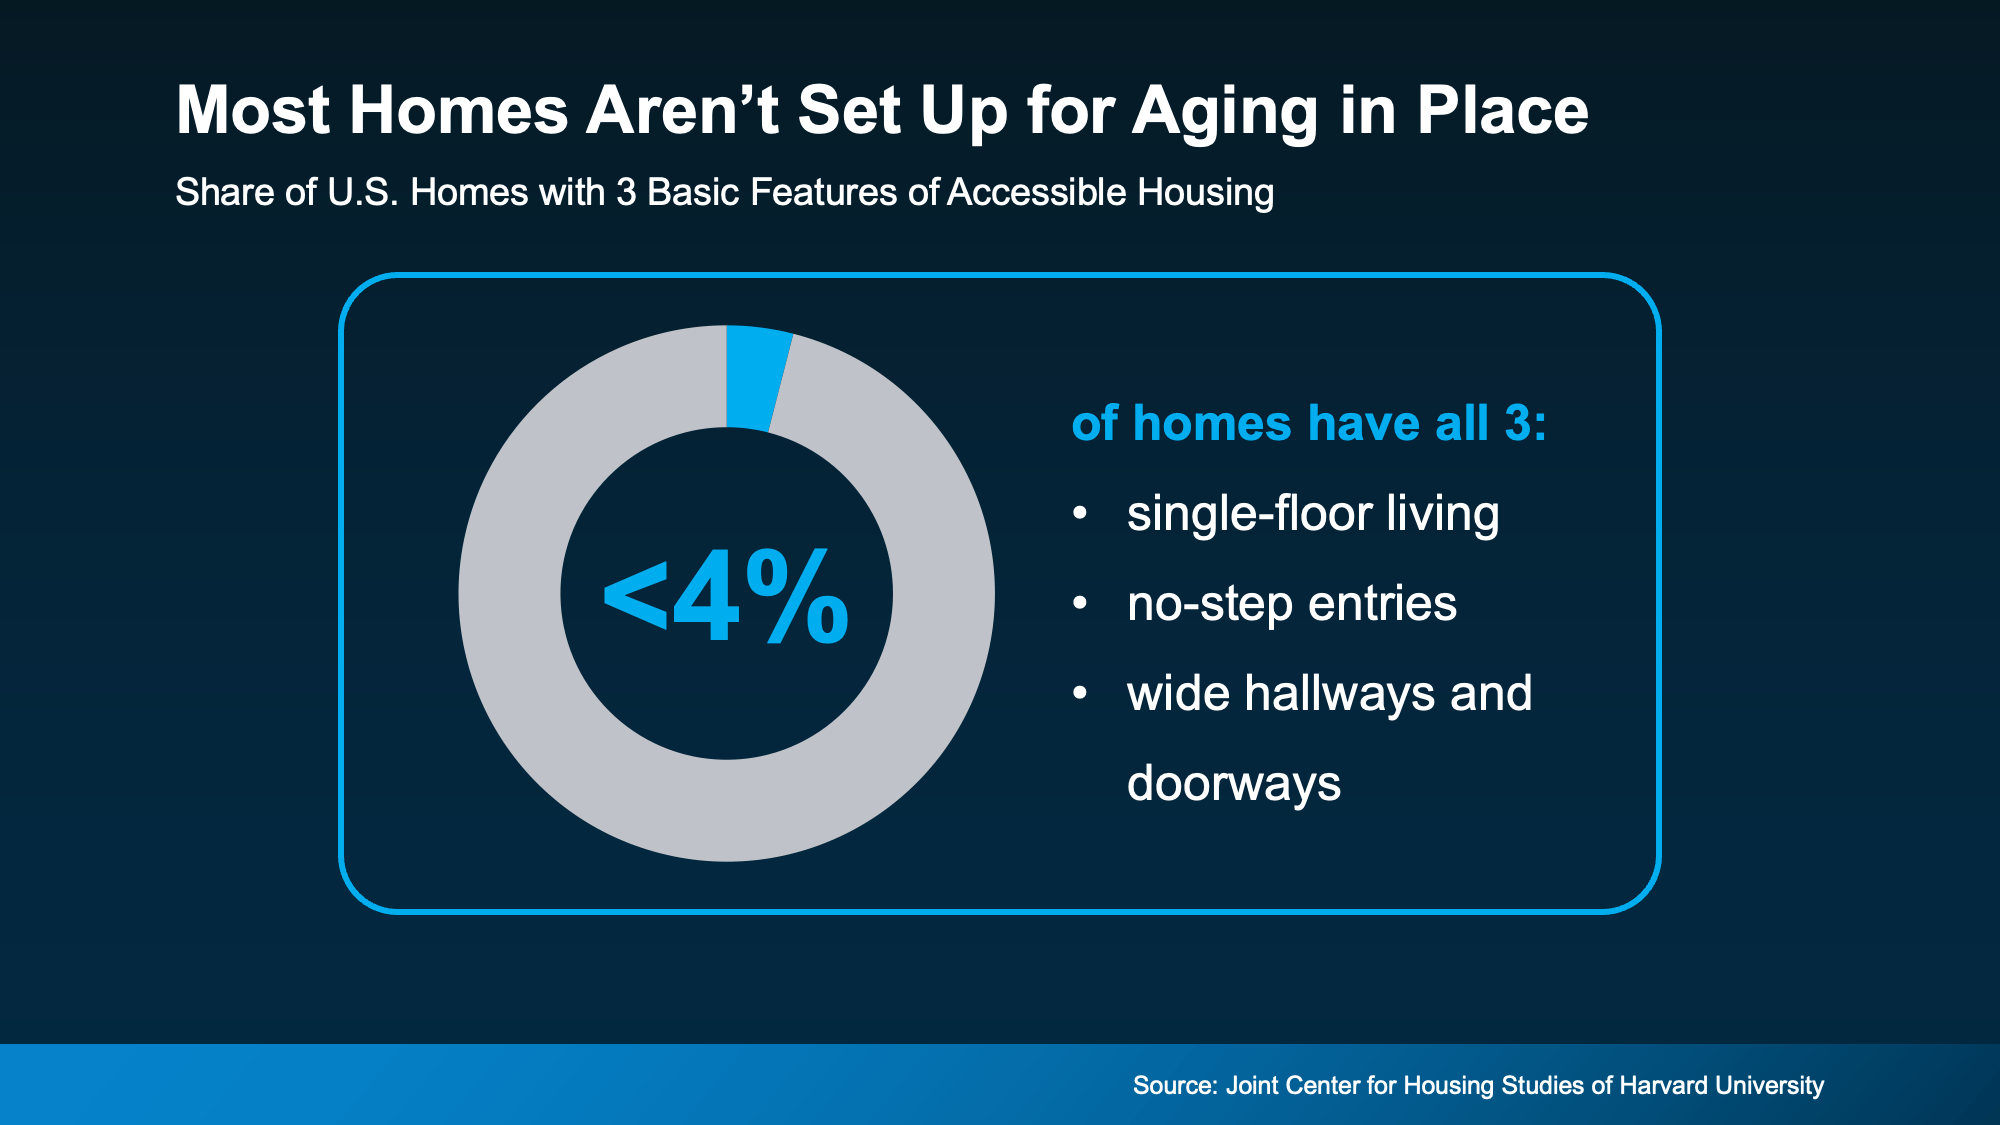
That means for most homeowners, staying put means doing a remodel.
The National Association of Home Builders (NAHB) reports more than half of remodelers (56%) take on this kind of work. Some of the most common projects are installing grab bars, curb-less showers (walk-in showers with no ledge to step over), and wider doorways.
Now, that’s not to say you can’t go this route. You most certainly can. But if this is how you’re leaning just know you’d be living with contractor noise and dust until the work gets done. Some people don’t want to live in a construction zone. Not to mention, having to manage the contractors and schedules, etc.
Your Equity Could Pay for Your Next Move
If that sounds like something you’d rather avoid, here’s the good news. The money for your next home may already be sitting in your current one. It’s called equity, which is the difference between what your house is worth and what you still owe on it. After years of mortgage payments and rising home values, it adds up. Jess Catorc, Co-Founder of Carry, explains:
“The way home equity builds and is used changes a lot depending on your stage of life. . . . For older homeowners, decades of mortgage payments and home-value growth can turn equity into a financial cushion.“
When you sell, that cushion can go toward a home that’s ready for this stage of life. No demo required. You just get the keys and it’s all there, ready for you. That means less time on projects and more time for living. And one option you may consider if you’re entertaining a move is a 55+ plus community.
Why 55+ Communities Are Worth a Look
From the homes to the shared spaces to the activity calendar, these communities are planned around this stage of life. And that means everything you need is already rolled into one place. Rocket Mortgage lists some of the biggest perks (see visual below):
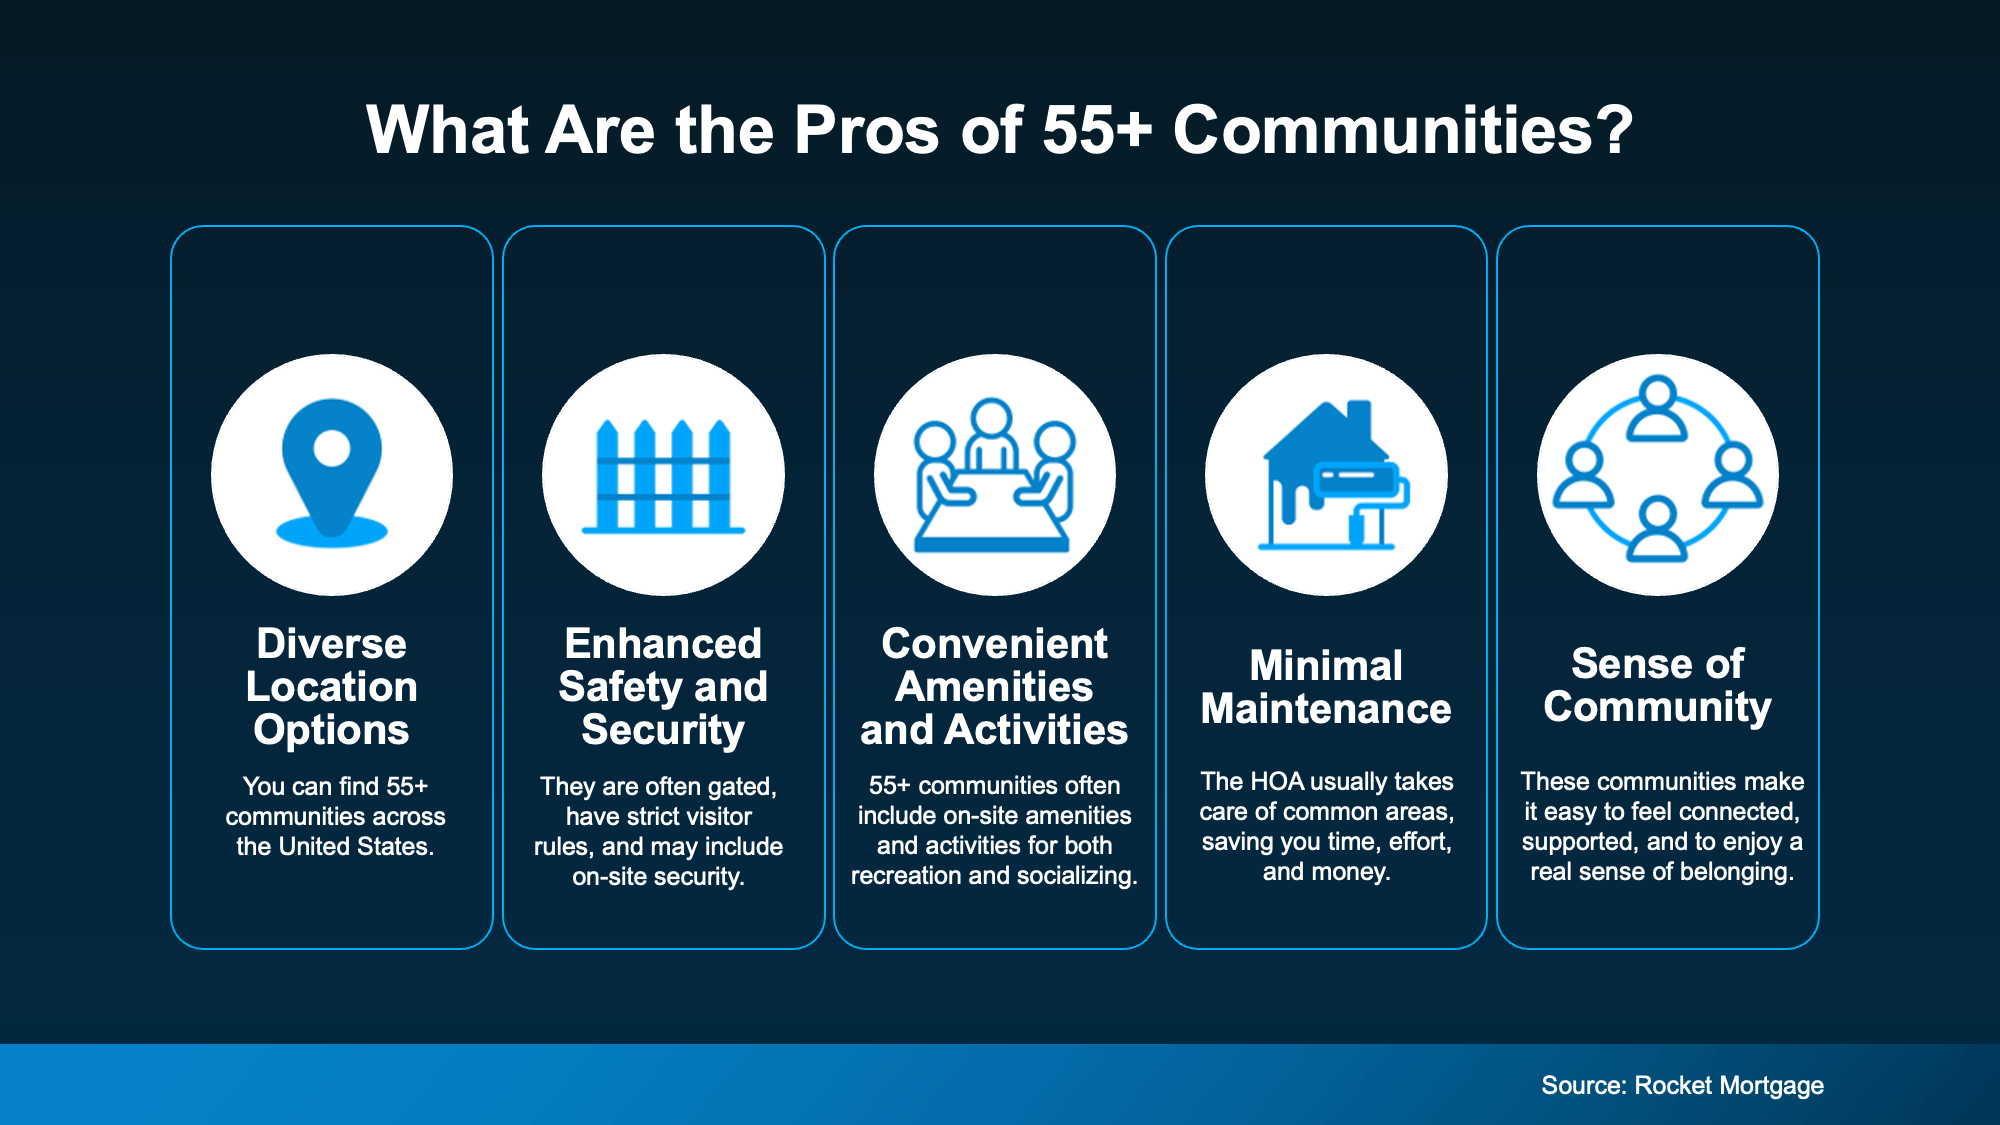
Instead of spending time and money to make your house easier to live in, you’d move into a community that’s designed with that in mind from the jump. That frees you up for the good stuff, like a morning walk with a neighbor, a game night down the street, or finally trying the hobby you’ve been putting off.
Bottom Line
Staying and moving can both be good choices. What matters most is finding the place where you’ll feel comfortable and at home for years to come.
If you’d like help weighing the two, let’s connect. We can look at what your house could sell for and what 55+ communities in our area have to offer, so you can decide what feels right for you.




